
American Express
American Express Membership Rewards Credit Card
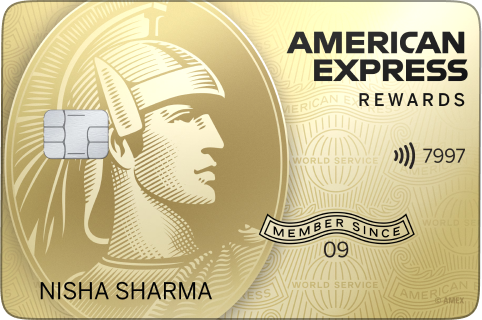
 This is an invite only card
Top Benefits

Earn 1 Membership Rewards Point for Every ₹50 Spent
redeemable for vouchers worth up to ₹14,000 (Taj) at 24,000 points via 18K and 24K Gold Collection
Earn 1,000 bonus Reward Points on making 4 transactions of ₹1,500+
in a month a recurring monthly bonus on top of regular reward earnings

Best For
Shopping
Dining
The American Express Membership Rewards Credit Card is one of the most rewarding entry-level cards in...
Read More Read Less

The American Express Membership Rewards Credit Card is one of the most rewarding entry-level cards in...
The American Express Membership Rewards Credit Card is one of the most rewarding entry-level cards in the Amex India lineup, built around the bank's globally renowned Membership Rewards programme. It carries a ₹1,000 joining fee and a ₹4,500 annual fee, with the annual fee fully waivable on annual spends of ₹1,50,000 or 50% waivable on spends of ₹90,000. So for a moderate spender hitting ₹1.5 lakh a year, this becomes effectively a ₹1,000 first-year card with rich rewards.
The earn structure is straightforward: 1 Membership Rewards Point for every ₹50 spent on eligible categories. That sounds modest until you account for the redemption multipliers. The best redemption value comes via the 24K Gold Collection: 24,000 MR Points fetch a Taj Hotels voucher worth ₹14,000, which works out to ₹0.58 per point, or a 1.16% effective return on every rupee spent. This rate beats most flat 1% cashback cards once you exclude their excluded MCCs.
The card is also rare for offering meaningful monthly milestone bonuses on top of base earning. Make 4 transactions of ₹1,500 or more in any calendar month and you earn 1,000 bonus MR points. Cross ₹20,000 in total monthly spend (enrollment required) and you earn another 1,000 bonus points. That is up to 2,000 bonus points monthly, worth ₹1,160 if redeemed through the Taj 24K voucher route, just for hitting low monthly thresholds.
Eligibility is moderate: ₹6 LPA minimum income for both salaried and self-employed, a CIBIL score of 720 or above, and an age range of 21 to 60 years. American Express also runs its own credit assessment in addition to the bureau check, so a clean repayment history matters even if your CIBIL is just above the threshold. The Amex network has narrower acceptance than Visa or Mastercard in India, especially at smaller merchants, so this card works best for those whose spending is concentrated at modern retail, e-commerce, dining, and travel.
View FAQ
Commonly Asked Questions
Q. What is the joining fee for the American Express Membership Rewards Credit Card?


A. The joining fee is ₹1,000 plus applicable GST, charged at the time of card issuance.
Q. Can the ₹4,500 annual fee be waived?
A. Yes, the annual fee is fully waived on annual spends of ₹1,50,000 or 50% waived on spends between ₹90,000 and ₹1,49,999 in the preceding membership year.
Q. What is the effective reward rate on this card?
A. With the best redemption (Taj 24K Gold Collection voucher), you get ₹0.58 per Membership Rewards Point, which equates to a 1.16% effective return on every ₹50 spent.

Expert Review
After reviewing the American Express Membership Rewards Credit Card across reward structure, fees, eligibility, and fit with Indian spending patterns, our verdict is that this is one of the most underrated entry-level reward cards in India. The combination of monthly milestone bonuses, strong base earning, and the Taj 24K Gold Collection redemption gives this card an effective return of 1.5% to 2% for moderate spenders, comparable to cards that charge two to three times the annual fee.
The key value driver is the milestone bonus structure. A user spending ₹20,000 a month with at least 4 transactions of ₹1,500 earns 400 base MR points (from ₹20,000 / ₹50) plus 2,000 milestone points, for 2,400 MR points monthly. That is 28,800 MR Points per year worth ₹16,704 at Taj redemption rate, against an annual cost of ₹0 (since spends exceed ₹1.5 lakh waiver threshold).
The card is not without limitations. Amex network acceptance in India is narrower than Visa or Mastercard, especially at smaller merchants, kirana stores, and local restaurants. The 3.5% forex markup is uncompetitive for international spenders. There is no airport lounge access, no movie ticket benefit, and no golf privilege, which keeps the card focused on rewards rather than experiential perks.
Our recommendation: get this card if you are a moderate spender (₹15,000 to ₹30,000 monthly) who shops at modern retail, dines at premium restaurants, and travels occasionally. Use it for spends where Amex is accepted, maintain at least 4 transactions of ₹1,500 monthly, and aim for the ₹1.5 lakh annual spend to waive the renewal fee.
As a secondary card alongside a Visa or Mastercard primary, this card delivers excellent value for milestone bonuses without the limitation of Amex acceptance for daily spends. The Membership Rewards programme is also one of the more flexible reward ecosystems globally, with strong partner transfers and a stable redemption catalogue.

Joining / Annual Fee
Joining Fees
₹1,180 ( ₹1000 + GST )

Annual Fees
₹5,310 ( ₹4500 + GST )
The American Express Membership Rewards Credit Card has a ₹1,000 joining fee charged at the time of c...
Read MoreRead Less
The American Express Membership Rewards Credit Card has a ₹1,000 joining fee charged at the time of c...
The American Express Membership Rewards Credit Card has a ₹1,000 joining fee charged at the time of card issuance, plus applicable GST. This is on the lower side for an Amex product (the Platinum Travel charges ₹5,000) and is justified by the welcome benefit of 4,000 MR Points on ₹1,000 spend within 30 days.
The annual fee is ₹4,500 plus applicable GST, levied from the second year onwards. The fee structure includes a tiered waiver: 100% waived on annual spends of ₹1,50,000 or more, 50% waived on spends between ₹90,000 and ₹1,49,999, and no waiver below ₹90,000. So for a moderate spender hitting ₹1.5 lakh a year (about ₹12,500 monthly), the renewal fee is effectively zero.
You also earn 5,000 MR Points on payment of the renewal fee (when not waived), which softens the cost. At the best redemption rate (Taj 24K voucher), these 5,000 points are worth ₹2,900, so the net cost of keeping the card is roughly ₹1,600 even if you do not hit the spend threshold for a waiver.
GST at 18% applies to both joining and annual fees, so the total first-year cost is ₹1,180 (₹1,000 + ₹180 GST). The annual fee from year two, if not waived, is ₹5,310 (₹4,500 + ₹810 GST).
View FAQ
Commonly Asked Questions
Q. What is the joining fee on this card?
A. The joining fee is ₹1,000 plus 18% GST, totalling ₹1,180 at the time of card issuance.
Q. What is the annual fee and how can it be waived?
A. The annual fee is ₹4,500 plus GST. It is fully waived on annual spends of ₹1,50,000 or more, 50% waived on spends between ₹90,000 and ₹1,49,999, and not waived below ₹90,000.
Q. Do I earn anything on renewal?
A. Yes, you earn 5,000 Membership Rewards Points on payment of the annual renewal fee, credited within 90 days of renewal.
Q. Is GST charged on the joining and annual fees?
A. Yes, 18% GST applies to both the joining fee and the annual fee.

Eligibility
Age
Criteria*
21-60 years
Salary
Criteria*
6LPA
Credit
Rating*
720+
New to credit
allowed
Yes
Existing Bank
Customer Allowed
Yes
American Express maintains slightly stricter eligibility for the Membership Rewards Credit Card than ...
Read MoreRead Less
American Express maintains slightly stricter eligibility for the Membership Rewards Credit Card than ...
American Express maintains slightly stricter eligibility for the Membership Rewards Credit Card than typical entry-level cards from Indian banks. Applicants must be between 21 and 60 years of age, applicable to both salaried and self-employed individuals.
The minimum annual income requirement is ₹6 LPA for both salaried and self-employed applicants, which translates to roughly ₹50,000 per month. Self-employed applicants need to support this with ITR filings of the last two years and ideally consistent business banking history.
A CIBIL score of 720 or above is required, but American Express also runs its own credit assessment. So even if your CIBIL just clears the threshold, the bank may decline if it sees recent defaults, excessive credit inquiries, settled accounts, or high revolving balances on existing cards.
You must be a resident Indian citizen with a valid PAN, Aadhaar, and address proof. American Express has a smaller card-issuing footprint compared to large Indian banks, so applications are typically processed for residents of major cities and tier-1 markets.
View FAQ
Commonly Asked Questions
Q. What is the minimum income required for the Amex Membership Rewards Credit Card?
A. The minimum annual income is ₹6 LPA for both salaried and self-employed applicants, supported by salary slips or ITR filings.
Q. What CIBIL score does Amex require?
A. A CIBIL score of 720 or above is required, but Amex also runs its own internal credit assessment beyond the bureau check.
Q. Can self-employed individuals apply for this card?
A. Yes, self-employed individuals between 21 and 60 years of age can apply, provided they meet the ₹6 LPA income criterion validated through ITR filings.
Q. Are NRIs eligible for this card?
A. No, this card is available only to resident Indian citizens. NRIs need to consider NRI-specific products.

All Card Benefits
- Get rewarded with Membership Rewards Points for all your transactions, redeemable for a variety of rewards
- Earn 4,000 Bonus Membership Rewards Points upon spending ₹1,000 within the first 30 days of card issuance
- Earn 1 Membership Reward Point for every ₹50 spent except on fuel, insurance, and utility bill payments
- Earn 1,000 Bonus Membership Rewards Points monthly by making 4 transactions of ₹1,500 or more
- Enjoy up to 20% off at select partner restaurants across India with exclusive American Express dining privileges
The card stacks four distinct earning layers, which is what makes it unusually rewarding for an entry...
Read MoreRead Less
The card stacks four distinct earning layers, which is what makes it unusually rewarding for an entry...
The card stacks four distinct earning layers, which is what makes it unusually rewarding for an entry-level Amex product. The base earn is 1 Membership Rewards Point per ₹50 spent on eligible categories, applicable to most retail, dining, travel, and online spends.
On top of that, there are monthly milestone bonuses. Make 4 transactions of ₹1,500 or more in a calendar month and you earn 1,000 bonus MR points (recurring monthly). Spend ₹20,000 or more in a calendar month (enrollment required) and you earn another 1,000 bonus points. So a moderate spender hitting both milestones every month earns an extra 24,000 MR Points per year, worth ₹13,920 at the best Taj redemption rate, just from bonuses.
Welcome benefits include 4,000 Bonus Membership Rewards Points on spending ₹1,000 within the first 30 days, which is essentially a free welcome gift worth ₹2,320 at the Taj redemption rate. On annual renewal, you also earn 5,000 Membership Rewards Points credited within 90 days of paying the renewal fee.
The card offers up to 20% off at select partner restaurants across India through the Amex dining programme. This is a useful benefit if you dine at premium restaurants regularly. The card also gives access to American Express merchant partner offers across shopping, dining, and entertainment categories, with rotating promotions throughout the year.
EMI options are available on eligible purchases. Convenience fee waivers apply at HPCL fuel stations (1% off). The card does not include complimentary airport lounge access, golf, or movie ticket benefits, which keeps it focused on rewards rather than experiential perks.
View FAQ
Commonly Asked Questions
Q. What is the base reward rate on this card?
A. You earn 1 Membership Rewards Point for every ₹50 spent on eligible categories, except fuel, insurance, and utility bill payments.
Q. How do the monthly bonus points work?
A. Make 4 transactions of ₹1,500 or more in a calendar month to earn 1,000 bonus points. Spend ₹20,000 or more in the same month (with enrollment) for another 1,000 bonus points, for up to 2,000 bonus points monthly.
Q. What is the welcome benefit on this card?
A. You earn 4,000 Bonus Membership Rewards Points on spending ₹1,000 within the first 30 days of card issuance.
Q. Is there a renewal benefit on the card?
A. Yes, you earn 5,000 Membership Rewards Points on payment of the annual fee from the second year onwards, credited within 90 days of renewal.
Q. Does this card offer airport lounge access?
A. No, the entry-level Membership Rewards Credit Card does not include complimentary airport lounge access. For lounge access, Amex offers the Platinum Travel Credit Card.
Q. Are there dining benefits on this card?
A. Yes, you get up to 20% off at select partner restaurants across India through the American Express dining programme.
Q. Can I convert spends into EMI?
A. Yes, you can convert eligible purchases into easy monthly EMI instalments at competitive interest rates.

Milestone Benefits

12000 reward points(Worth ~ ₹4,680)
Spend ₹6,000 in 30 days
12000 reward points(Worth ~ ₹4,680)
Spend ₹20,000 in 30 days

How to Redeem Rewards & Cashback?
Rewards Conversion Rate
1 Reward Point = ₹0.40

Redemption Options
- E-Vouchers
- Travel (Flights/Hotels)
- Partner Transfers
- Statement Credit
- Pay with Points
To check redemption catalogue
The American Express Membership Rewards programme is one of the most flexible redemption ecosystems a...
Read MoreRead Less
The American Express Membership Rewards programme is one of the most flexible redemption ecosystems a...
The American Express Membership Rewards programme is one of the most flexible redemption ecosystems available on any Indian credit card. You can redeem Membership Rewards Points across e-vouchers, travel bookings (flights and hotels), airline and hotel partner transfers, statement credit, and pay-with-points at merchant checkouts.
The best redemption value comes through the 24K Gold Collection: 24,000 MR Points fetch a Taj Hotels voucher worth ₹14,000 (₹0.58 per point). Other 24K options include Shoppers Stop ₹10,000, Tata CLiQ ₹9,000, Tanishq ₹9,000, Amazon ₹8,000, Flipkart ₹8,000, and Reliance Digital ₹8,000. The 18K Gold Collection offers smaller denominations: 18,000 MR Points for ₹9,000 Taj voucher, ₹7,000 Shoppers Stop, ₹7,000 Tata CLiQ, ₹7,000 Myntra, and ₹6,000 each for Amazon, Flipkart, and Reliance Digital.
To redeem, log in to the Amex Rewards portal at americanexpress.com/india/rewards, browse the catalogue, select your preferred voucher, and confirm. E-vouchers are typically delivered to your registered email within 24 to 72 hours. There is a redemption handling fee of ₹99 plus GST per request, so it makes sense to redeem in larger batches.
You can also transfer MR Points to airline partners like InterMiles (1 MR = 1 InterMiles), Marriott Bonvoy, and select hotel programmes. The transfer rates vary, so check the latest partner table on the Amex India rewards page before transferring.
Points do not expire as long as the card account is active and in good standing. There is no monthly cap on redemption, but minimum redemption thresholds (typically 1,000 or 1,800 points) apply for certain partners and vouchers.
View FAQ
Commonly Asked Questions
Q. What is the best redemption value on this card?
A. The best value is through the 24K Gold Collection: 24,000 MR Points for a Taj Hotels voucher worth ₹14,000, giving ₹0.58 per point or a 1.16% effective return.
Q. Is there a redemption fee?
A. Yes, a redemption handling fee of ₹99 plus applicable GST is charged per redemption request. Redeeming in larger batches is more cost-efficient.
Q. Do Membership Rewards Points expire?
A. No, MR Points do not expire as long as the card account is active and in good standing. This gives you full flexibility to accumulate for larger redemptions.

Bank Exclusions
You will not earn points / cashback on spends in the following categories
For Points / Cashback Earnings

Rent payment
Fuel
EMI Transactions
Cash Withdrawals
Jewellery
Government related transactions
Wallet transactions - Load money
Fees
GST charges
All Reversals
Gambling
Tolls
Security Broker Services
Charity
Railways
Utility Bill Payments
For Spends Waiver
Rent payment
Fuel
EMI Transactions
Cash Withdrawals
Jewellery
Government related transactions
Wallet transactions - Load money
Fees
GST charges
All Reversals
Gambling
Tolls
Security Broker Services
Charity
Railways
Utility Bill Payments
The American Express Membership Rewards Credit Card has a defined list of categories where rewards ar...
Read MoreRead Less
The American Express Membership Rewards Credit Card has a defined list of categories where rewards ar...
The American Express Membership Rewards Credit Card has a defined list of categories where rewards are not earned. Understanding these helps you set realistic earning expectations.
Excluded categories include rent payments, fuel transactions, insurance premium payments, EMI transactions, cash withdrawals, jewellery purchases, school and educational services, government-related transactions, wallet transactions (load money), bank fees, GST charges, and all reversals. These do not earn any base rewards or milestone bonuses.
Additional exclusions cover gambling, tolls, security broker services, charity, railways, and utility bill payments. So if a large portion of your monthly spend goes into utilities (electricity, water, broadband), you would not earn any MR Points on those transactions. This is a meaningful gap compared to cards like the Axis ACE which give accelerated cashback on utility payments.
The card excludes all reversals, which means cancelled or refunded transactions do not retain their earned points. So if you make a ₹10,000 booking and cancel it, the 200 MR Points earned would be reversed in the next statement cycle.
The bank reserves the right to exclude any merchant or MCC at its discretion. Always refer to the latest MITC document for the full exclusion list.
View FAQ
Commonly Asked Questions
Q. Are utility bill payments excluded from rewards on this card?
A. Yes, utility bill payments are excluded from earning Membership Rewards Points on this card.
Q. Do rent payments earn rewards?
A. No, rent payments are excluded from rewards. Additionally, a 2% processing charge applies on rent payments through fintech apps.
Q. Are insurance premium payments rewarded?
A. No, insurance premium payments are excluded from earning MR Points on this card.

Bank Fee Structure
| Structure | Details |
|---|---|
Forex Markups  3.50% forex markup is charged on transactions made in currencies other than INR. Applies to international POS payments and online purchases charged in foreign currency | 3.50% |
APR Fees 3.50% monthly interest rate applies on the outstanding balance if the full amount due is not paid by the statement due date. The interest-free period is 20 to 55 days for new purchases | 3.50% |
ATM withdrawal 3.50% of the withdrawn amount is charged on cash advances using the credit card | 3.50% |
Reward Redemption Fees A reward redemption handling fee of ₹99 plus applicable GST is charged per redemption request | ₹99 |
Link for all T&Cs | Click Here |
Railway Surcharge A railway booking surcharge of 1.80% for online transactions and 2.50% for other bookings is applied, with additional bank charges and taxes recovered at actuals | 1.80% |
Rent Payment Fees 2% of the transaction amount is charged as a fee on rent payment transactions, subject to applicable GST and platform charges | 2% |
cheque Payment Fees A fee of ₹250 is charged for payments made by cheque | ₹250 |
Cash Payment Fees A fee of ₹100 is charged for payments made by depositing cash at a bank branch or ATM | ₹100 |
| Late Payment Fees | Amount Due |
|---|---|
| ₹0–100 | ₹0 |
| ₹101–500 | ₹500 |
| ₹501–1,000 | ₹750 |
| ₹1,001–5,000 | ₹1,000 |
| Above ₹5,000 | ₹1,200 |
Here is a complete breakdown of all the charges associated with the American Express Membership Rewar...
Read MoreRead Less
Here is a complete breakdown of all the charges associated with the American Express Membership Rewar...
Here is a complete breakdown of all the charges associated with the American Express Membership Rewards Credit Card.
The joining fee is ₹1,000 plus applicable GST, charged at the time of card issuance. This is offset partially by the 4,000 welcome bonus MR Points earned on ₹1,000 spend in 30 days, which are worth ₹2,320 at Taj redemption rate.
The annual fee is ₹4,500 plus applicable GST, levied from year two onwards. The fee is fully waived on annual spends of ₹1,50,000 or 50% waived on spends between ₹90,000 and ₹1,49,999. So a ₹1.5 lakh annual spender pays effectively zero from year two onwards.
Forex markup is 3.5% on all international transactions. If you spend USD 100 (about ₹8,300), you would pay an additional ₹290 as forex markup. This is industry-standard for Amex cards in India but not differentiated for travel spenders.
Annual percentage rate (APR) on revolving balances is 3.75% per month, which translates to 55.55% per annum (one of the higher rates in the market). If you carry forward ₹10,000 of unpaid dues, you would be charged ₹375 in interest in the next billing cycle. Always pay your full statement balance to avoid this.
ATM cash advance fee is 2.5% of the withdrawn amount, with a minimum of ₹500. Withdrawing ₹5,000 would cost you ₹500 as fee, plus interest from the day of withdrawal at 3.75% per month.
Reward redemption fee is ₹99 plus applicable GST per redemption request. So if you redeem 5,000 points (worth about ₹2,900 at best rate), the net you receive is about ₹2,800 after deducting the redemption fee.
Railway booking surcharge is 1.80% for online transactions and 2.50% for other bookings, with additional bank charges and taxes recovered at actuals. This is on top of any IRCTC convenience fees.
Rent payment processing charge is 2% of the transaction value when paying rent through fintech apps, plus applicable GST. A ₹25,000 rent payment costs ₹500 in processing charges, on top of zero rewards earned. This is higher than the 1% charged by many other cards.
Cheque payment charge is ₹0 on this card. You can pay your bill via cheque without any deduction. Cash payment at branch carries ₹100 plus applicable GST per transaction.
Late payment charges are slab-based: ₹0 below ₹500, ₹500 for ₹501 to ₹5,000, ₹750 for ₹5,001 to ₹10,000, and ₹1,200 for balances above ₹10,000.
| Fee Type | Amount |
|---|---|
| Joining Fee | ₹1,000 + GST |
| Annual Fee | ₹4,500 + GST (waived on ₹1.5L) |
| Forex Markup | 3.5% |
| APR | 3.75% per month (55.55% p.a.) |
| Cash Advance Fee | 2.5% (min ₹500) |
| Reward Redemption Fee | ₹99 + GST per request |
| Railway Surcharge | 1.80% online / 2.50% offline |
| Rent Payment Charge | 2% of transaction |
| Cheque Payment Charge | ₹0 |
| Cash Payment at Branch | ₹100 + GST |
| Late Payment Charges | ₹0 / ₹500 / ₹750 / ₹1,200 (slab-based) |
View FAQ
Commonly Asked Questions
Q. What is the interest rate on this card?
A. The interest rate is 3.75% per month, which works out to 55.55% per annum on revolving balances. Paying your full statement balance avoids these charges entirely.
Q. What is the forex markup on this card?
A. The forex markup is 3.5% on all international transactions, added to the converted INR value at the bank's exchange rate.
Q. What are the late payment charges?
A. Late payment charges are slab-based: ₹0 below ₹500, ₹500 for ₹501 to ₹5,000, ₹750 for ₹5,001 to ₹10,000, and ₹1,200 for balances above ₹10,000.
Q. What is the rent payment charge?
A. Rent payments through fintech apps attract a 2% processing charge plus applicable GST. Rent payments also do not earn any rewards.
Q. Is there a reward redemption fee?
A. Yes, a redemption fee of ₹99 plus GST is charged per redemption request. Redeeming in larger batches is more cost-efficient.
Q. What is the cash advance fee?
A. The cash advance fee is 2.5% of the withdrawn amount, with a minimum of ₹500. Interest also accrues from the day of withdrawal at 3.75% per month.

Documents Required
To apply for the American Express Membership Rewards Credit Card, you need to submit identity proof, address proof, and income proof documents. Most can be uploaded digitally during the online application.
Identity proof requires PAN (mandatory) plus any one of Aadhaar, Voter ID, passport, or driving licence. Address proof can be Aadhaar with current address, recent utility bills (electricity, water, gas) not older than 3 months, rental agreement, passport, or driving licence with the correct address.
Income proof for salaried applicants includes the last 3 months' salary slips and the last 6 months' bank statement showing salary credits. Self-employed applicants need to submit the last 2 years' ITR with computation, latest 6 months' business bank statement, and proof of business existence such as a GST certificate or partnership deed.
You may also need to provide a recent passport-size photograph (digital upload during online application) and existing credit card statements (if any) to demonstrate credit history.
View FAQ
Commonly Asked Questions
Q. Is PAN mandatory for the application?
A. Yes, PAN is mandatory as per RBI regulations for all credit card applications in India.
Q. What income proof is needed for salaried applicants?
A. Salaried applicants need the last 3 months' salary slips and the last 6 months' bank statement showing salary credits.
Q. What income proof is needed for self-employed applicants?
A. Self-employed applicants need the last 2 years' ITR with computation, 6 months' business bank statement, and proof of business existence like a GST certificate.

Who Should Get This Card?
The American Express Membership Rewards Credit Card is a strong fit for moderate spenders who want flexible reward redemption with meaningful value. If your monthly spending is around ₹15,000 to ₹30,000 mostly at modern retail, e-commerce, dining, and travel, this card slots in well as a primary card.
The monthly milestone structure makes this card especially rewarding for users who can easily hit 4 transactions of ₹1,500 and ₹20,000 monthly spend. That earns up to 24,000 bonus MR points per year (worth ₹13,920 at Taj redemption rate) on top of base earning, which is substantial for an entry-level card.
The card also suits users who already shop or stay at Taj Hotels, Shoppers Stop, Tata CLiQ, Tanishq, or Reliance Digital, as the 24K Gold Collection vouchers redeem at their best value. If you redeem MR Points for Amazon or Flipkart vouchers, the redemption rate drops to ₹0.40 per point.
This card is not the right pick if your spending is concentrated in excluded categories like utilities, rent, fuel, insurance, or education. In that case, look at cards like the Axis ACE (utilities), HDFC Tata Neu Infinity (rent), or BPCL SBI Octane (fuel). Similarly, if Amex network acceptance is a concern in your daily merchant ecosystem (smaller shops, kiranas, local restaurants), a Visa or Mastercard would be more practical.
As a secondary card alongside a Visa or Mastercard primary, the Amex Membership Rewards adds value for premium retail, dining, and travel spends where Amex is accepted. Many users keep this card specifically for milestone bonuses while using another card for everyday spends.

Credit Limit and What to Expect
The credit limit on the American Express Membership Rewards Credit Card depends on your declared income, CIBIL score, existing credit obligations, and Amex's internal scoring model. For a ₹6 to ₹10 LPA income profile, typical starting limits range from ₹1,00,000 to ₹3,00,000.
Amex is known for offering "no preset spending limit" (NPSL) on some of its products, meaning the card has flexibility for higher transactions if your spending pattern and payment history justify it. However, this feature is more common on the higher-tier Platinum cards and may not apply to the Membership Rewards variant in India.
Amex reviews accounts periodically and offers credit limit enhancements after 6 to 12 months of regular usage and timely payments. You can also request an enhancement directly by calling customer care or through the online portal. Enhancements of 20% to 50% are common for cardholders with strong spend and payment patterns.
Within your overall limit, there is also a cash advance limit, usually 20% to 40% of your credit limit, attracting a 2.5% fee with a minimum of ₹500. Cash advances should be treated as an emergency-only feature due to immediate interest accrual.
View FAQ
Commonly Asked Questions
Q. What credit limit can I expect on this card?
A. For ₹6 to ₹10 LPA income profiles, starting limits typically range from ₹1,00,000 to ₹3,00,000 depending on your CIBIL score and existing credit profile.
Q. Does Amex offer "no preset limit" on this card?
A. The no preset spending limit feature is more common on Amex's Platinum products. The Membership Rewards Credit Card typically has a defined credit limit.
Q. How do I request a credit limit increase?
A. You can request a credit limit increase after 6 to 12 months of regular usage by calling Amex customer care or through the online portal.

How to Apply?
You can apply for the American Express Membership Rewards Credit Card through the Amex India website, partner platforms like BankKaro that often run additional welcome offers, or by calling the Amex India customer service line for application assistance.
The online application via americanexpress.com is the most common route. Visit the credit cards page, select the Membership Rewards variant, click Apply Now, and fill in PAN, Aadhaar, date of birth, employment type, and monthly income. Upload digital copies of your PAN, Aadhaar, latest 3 months' salary slips (for salaried) or last 2 ITR documents (for self-employed), and address proof.
American Express runs both a bureau check and an internal credit assessment, so the initial decision may take 3 to 5 working days, longer than Indian banks. If approved, you complete KYC, which may involve a phone verification or video KYC depending on your profile. The physical card is dispatched within 7 to 14 working days to your registered address.
For high-touch service, you can also request a relationship manager callback through the Amex website. Amex is known for white-glove servicing on its cards, including dedicated customer support for applications.
View FAQ
Commonly Asked Questions
Q. Can I apply for this card online?
A. Yes, you can apply through the Amex India website at americanexpress.com, partner platforms like BankKaro, or by calling Amex customer service.
Q. How long does it take to receive the card?
A. The physical card is dispatched within 7 to 14 working days after final approval. Approval itself may take 3 to 5 working days due to Amex's internal credit assessment.
Q. Is video KYC required for the application?
A. Some applications require video KYC while others use a phone verification. The method depends on your profile and the application channel.

That’s the full story of this credit card
Like this card? Your apply button’s just there.
Top Benefits
Top Benefits
Earn 1 Membership Rewards Point for Every ₹50 Spent
redeemable for vouchers worth up to ₹14,000 (Taj) at 24,000 points via 18K and 24K Gold Collection
Earn 1,000 bonus Reward Points on making 4 transactions of ₹1,500+
in a month a recurring monthly bonus on top of regular reward earnings

The smartest way to find your great credit card


We value your time and privacy. Your details stay secure and are used only to help you.
Company
We value your time and privacy. Your details stay secure and are used only to help you.