
Axis
Axis MyZone Credit Card
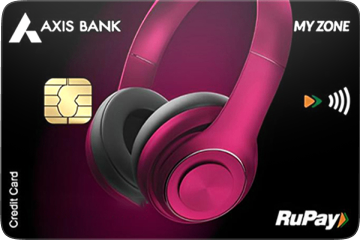
 This is an invite only card


Apply and get ₹1400 Rewards

Top Benefits

Get Movie Ticket Free on Your Second District Booking with Coupon AXIS200
capped at ₹200 per month and with no reward points on movie transactions
Get ₹120 Off on Swiggy Orders With Coupon AXIS120
on minimum spends of ₹500, capped at ₹120 per order and redeemable up to 2 times a month per user

Best For
Shopping
Online Food Ordering
Travel
The Axis MyZone Credit Card is built for one specific kind of spender. The young, urban, OTT-streaming,...
Read More Read Less

The Axis MyZone Credit Card is built for one specific kind of spender. The young, urban, OTT-streaming,...
The Axis MyZone Credit Card is built for one specific kind of spender. The young, urban, OTT-streaming, weekend-movie-going, occasional-flight-booking type who wants a simple lifestyle card without paying premium-card fees. With a low joining fee of ₹500 and a Sony LIV Premium annual subscription as the welcome gift, this card practically pays for itself before you start spending.
What makes the Axis MyZone Credit Card different from the swarm of entry-level rewards cards in India is its entertainment-first pitch. You get a free Sony LIV Premium subscription worth ₹1,499 on your first transaction within 30 days, up to 15% off on flights via MakeMyTrip on Wednesdays, dining discounts of 15% (up to ₹500) through Axis Bank Dining Delights, and one complimentary domestic airport lounge visit every calendar quarter. Add 4 EDGE Reward points on every ₹200 spent and an annual milestone bonus of 1,000 EDGE points, and you have a card that genuinely earns its keep for someone spending around ₹15,000 to ₹25,000 a month.
The Axis MyZone Credit Card is positioned for first-jobbers and salaried professionals earning at least ₹25,000 a month. It is not the card for someone chasing accelerated cashback on online shopping, or for a high spender who wants premium lounge access on every visit. Think of it as a starter lifestyle card that gives you a taste of the good stuff without locking you into a five-figure annual fee.
View FAQ
Commonly Asked Questions
Who is the Axis MyZone Credit Card best suited for?


The Axis MyZone Credit Card is best for young salaried professionals between 21 and 35 years of age who watch OTT content, eat out twice a month, and book a few domestic flights a year. If your monthly card spend sits between ₹15,000 and ₹30,000 and you want lifestyle perks without paying a premium card fee, this card fits well.
Is the Axis MyZone Credit Card a lifetime free credit card?
The Axis MyZone Credit Card carries a joining fee of ₹500 and an annual fee of ₹500. The annual fee is waived if you spend ₹1.5 lakh or more in a year. Axis Bank does run lifetime free promotional offers on this card through select channels and account bundles, so it is worth checking the current offer before you apply.
What is the welcome benefit on the Axis MyZone Credit Card?
You get a complimentary Sony LIV Premium annual subscription worth ₹1,499 on making your first transaction within 30 days of card issuance. That single benefit covers three times the joining fee, which makes the card effectively free in year one for any active user.
How many reward points do I earn per ₹100 on the Axis MyZone Credit Card?
You earn 4 EDGE Reward points on every ₹200 spent, which works out to 2 points per ₹100. With each EDGE point worth ₹0.25, that translates to a flat reward rate of 0.5% on most retail spends. So a monthly spend of ₹20,000 earns you 400 EDGE points, worth ₹100 in redeemable value.

Expert Review

Joining / Annual Fee
Joining Fees
₹590 ( ₹500 + GST )

Annual Fees
₹590 ( ₹500 + GST )
The Axis MyZone Credit Card carries a joining fee of ₹500 and an annual fee of ₹500. Both amounts are e...
Read MoreRead Less
The Axis MyZone Credit Card carries a joining fee of ₹500 and an annual fee of ₹500. Both amounts are e...
The Axis MyZone Credit Card carries a joining fee of ₹500 and an annual fee of ₹500. Both amounts are exclusive of GST. The joining fee is charged in the first statement after card issuance and is not directly offset by any specific bonus or credit. However, the welcome benefit (Sony LIV Premium worth ₹1,499) easily covers the fee three times over for any active user.
The annual fee is waived if you spend ₹1.5 lakh or more in a card anniversary year. That works out to ₹12,500 a month in eligible spending. For a salaried professional using this as a primary card for shopping, dining, and travel, the threshold is realistic and unlocks the fee waiver naturally.
If you do not hit ₹1.5 lakh in annual spends, the ₹500 fee is charged in your renewal cycle. To frame the math simply: the Sony LIV welcome benefit alone gives you ₹1,499 in year one, and the dining and travel discounts can comfortably add ₹2,000 to ₹3,000 in savings for an active user. So even if you pay the ₹500 annual fee, you stay net positive on the card.
Axis Bank does occasionally offer the Axis MyZone Credit Card as a Lifetime Free card through promotional bundles, salary account programmes, and partner channels. If you are eligible for one of these offers, the joining fee and annual fee are both fully waived for the life of the card.
View FAQ
Commonly Asked Questions
What is the joining fee of the Axis MyZone Credit Card?
The joining fee is ₹500 plus GST. Once paid, you become eligible for the Sony LIV Premium welcome benefit on your first transaction within 30 days.
What is the annual fee on this card?
The annual fee is ₹500 plus GST, charged on the first card anniversary. The fee is waived if your annual spending crosses ₹1.5 lakh in the previous card year.
How is the annual fee waiver calculated?
The bank tracks your total spends from the date of card activation to the next card anniversary. If the cumulative eligible spend touches ₹1.5 lakh, the next year's annual fee is automatically reversed in your statement.
What spends count towards the ₹1.5 lakh fee waiver?
Standard retail spends count, including shopping, dining, travel, and partial bill payments. Excluded categories like fuel, EMI conversions, wallet loads, rent, and government payments do not contribute towards the ₹1.5 lakh waiver target.
How much do I need to spend monthly to hit the fee waiver?
You need to average ₹12,500 a month in eligible spends across 12 months to clear the ₹1.5 lakh annual threshold. For most urban salaried users, that is roughly equivalent to using this card as a primary plastic for shopping and bill payments.
Are the joining and annual fees refundable?
The joining fee is not refundable once charged, since it is tied to card issuance. The annual fee is reversed only if the spend-based waiver condition is met during the previous card year.
Is GST charged on the joining and annual fees?
Yes, 18% GST is added on top of both the ₹500 joining fee and the ₹500 annual fee. So the actual amount that hits your statement is ₹590 each, including taxes.
Does the card come with a lifetime free option?
The standard variant carries a ₹500 joining and ₹500 annual fee. Axis Bank periodically offers Lifetime Free promotions on this card through specific channels and account bundles, but these are time-bound and partner-specific.

Eligibility
Age
Criteria*
21-65 years
Salary
Criteria*
3LPA
Credit
Rating*
720+
New to credit
allowed
Yes
Existing Bank
Customer Allowed
Yes
Axis Bank keeps the Axis MyZone Credit Card eligibility quite friendly to first-time credit card applic...
Read MoreRead Less
Axis Bank keeps the Axis MyZone Credit Card eligibility quite friendly to first-time credit card applic...
Axis Bank keeps the Axis MyZone Credit Card eligibility quite friendly to first-time credit card applicants. The age and income requirements sit on the lower side compared to most other Visa lifestyle cards, which is what makes it a popular pick for people building their credit profile.
The age window is 21 to 65 years for both salaried and self-employed applicants. The minimum monthly income required is ₹25,000, and Axis Bank looks for an annual income of around ₹3 lakh for salaried applicants and ₹3.6 lakh for self-employed applicants. A CRIF or CIBIL score of 735 or higher is preferred, which most professionals with a clean repayment history of one to two years will already have.
To put this in perspective, a ₹25,000 monthly salary qualifies you, which most entry-level urban jobs in India easily clear. Self-employed applicants with a small business or freelance practice generating ₹30,000 a month and clean ITR filings are also good candidates.
The card supports both Indian residents and salaried plus self-employed applicants. NRIs are not in the standard eligibility pool for this card.
| Criterion | Salaried | Self Employed |
|---|---|---|
| Minimum Age | 21 years | 21 years |
| Maximum Age | 65 years | 65 years |
| Minimum Monthly Income | ₹25,000 | ₹30,000 equivalent |
| Minimum Annual Income | ₹3 lakh | ₹3.6 lakh |
| CIBIL / CRIF Score | 735+ | 735+ |
| Residency | Indian Resident | Indian Resident |
View FAQ
Commonly Asked Questions
What is the minimum salary required for the Axis MyZone Credit Card?
The minimum monthly salary required is ₹25,000, with an indicative annual income of ₹3 lakh for salaried applicants. Self-employed applicants need ITR-backed annual income of at least ₹3.6 lakh for a higher approval probability.
What is the minimum age for this card?
The minimum age is 21 years and the maximum age is 65 years for both salaried and self-employed applicants. So a fresh graduate in their first job is well within the eligibility window.
What CIBIL score do I need for the Axis MyZone Credit Card?
A credit score of 735 or higher gives you a strong approval chance. If your CIBIL is between 700 and 735, you may still be approved with a lower credit limit, especially if your income is well above the minimum and you have a steady employment history.
Can self-employed people apply for this card?
Yes, self-employed individuals are eligible. The bank looks at your latest two years of ITR and bank statements to assess income stability. A net annual income of ₹3.6 lakh is the working benchmark for approval.
Can a student apply for this card?
Students without a regular income source are not eligible for the Axis MyZone Credit Card directly. A student with a part-time job earning ₹25,000 a month or above can apply, otherwise the option is to take an add-on card on a parent's primary card.
Do I need to be an Axis Bank account holder to apply?
No, you do not need an existing Axis Bank account to apply for this card. Both Axis Bank customers and non-customers can apply through the website or app, although having an Axis Bank salary account can speed up KYC and approvals.
Is there an add-on card option?
Yes, Axis Bank lets you issue add-on cards for immediate family members on the Axis MyZone Credit Card. The add-on card shares the credit limit and reward earnings of the primary card, but lounge benefits are restricted to the primary cardholder.
What documents are required during the application?
You need a PAN card, Aadhaar card, recent salary slips (3 months) or latest ITR, and 6 months of bank statements. Self-employed applicants additionally provide their business proof, GST registration, and updated ITR for the last two years.

All Card Benefits
- Earn 4 EDGE REWARD points per ₹200 spent
- 1,000 EDGE REWARD points on annual spends of ₹1.5 lakh
- 1 complimentary airport lounge visit per quarter ₹50,000 spend condition
- Up to 15% discount on flights via MakeMyTrip Wednesday offer
- Dining offers 15% off up to ₹500 via Axis Bank Dining Delights program
The Axis MyZone Credit Card builds its value across five clear pillars: a strong welcome gift, OTT ente...
Read MoreRead Less
The Axis MyZone Credit Card builds its value across five clear pillars: a strong welcome gift, OTT ente...
The Axis MyZone Credit Card builds its value across five clear pillars: a strong welcome gift, OTT entertainment perks, dining and movie offers, travel discounts, and an airport lounge benefit. Below is a breakdown of each so you can map the perks against your own spending pattern.
Welcome Benefits
The headline welcome benefit is a complimentary Sony LIV Premium annual subscription worth ₹1,499. This is unlocked when you make your first transaction on the card within 30 days of issuance. The subscription is delivered as a digital voucher to your registered email and gives you access to live sports, originals, premium shows, and movies on Sony LIV for one full year.
For perspective, the Sony LIV Premium plan retails at around ₹999 to ₹1,499 a year depending on the package. So if you would have subscribed anyway, the Axis MyZone Credit Card refunds your subscription cost plus more, on top of letting you keep the card.
Reward Points Structure
The Axis MyZone Credit Card uses Axis Bank's EDGE Rewards programme. You earn 4 EDGE Reward points on every ₹200 spent on the card, which means 2 points per ₹100. Each EDGE Reward point converts to ₹0.25, so the effective base reward rate is 0.5% on eligible spends.
Let us put that in real numbers. If you spend ₹15,000 a month on the card across groceries, online shopping, and dining, you earn 300 EDGE points a month, or 3,600 points a year. At ₹0.25 per point, that is ₹900 in redeemable value annually. Add the milestone bonus of 1,000 EDGE points (worth ₹250) on annual spends of ₹1.5 lakh and you cross ₹1,150 in pure rewards before you count the welcome benefit, dining offers, or flight discounts.
The bigger picture is that this card is not a rewards beast. The 0.5% base rate trails entry-level cashback cards like the Amazon Pay ICICI or HDFC MoneyBack+, which can deliver 1.5% to 5% on online spends. The Axis MyZone makes its money back through the welcome benefit and lifestyle perks, not raw points.
Airport Lounge Access
The Axis MyZone Credit Card offers 1 complimentary domestic airport lounge visit per calendar quarter, taking your annual count to 4 lounge visits. Access is available at select participating lounges across major Indian airports. There is a spend-based eligibility condition: you must spend ₹50,000 or more in the previous 3 months to unlock that quarter's lounge visit.
Practically, this means a monthly spend of about ₹17,000 keeps the lounge benefit alive. For a card with a ₹500 fee, that is a fair trade. If a paid lounge visit costs ₹1,000 to ₹1,500, four such visits a year amount to ₹4,000 to ₹6,000 in saved value, far exceeding the card's annual fee.
Flight Booking Benefits
The card offers up to 15% instant discount on flight bookings made through MakeMyTrip on Wednesdays under the "Wednesday Delight" offer. This is a valuable perk for someone who can plan their flight bookings around midweek.
Example: a domestic round-trip ticket of ₹8,000 would attract a discount of up to ₹1,200 if you book it on a Wednesday with this card. Two such bookings a year cover the annual fee three times over. The discount carries an upper cap (₹1,500 to ₹2,000 per booking depending on the active campaign), so check the offer page on MakeMyTrip before you confirm the ticket.
Dining and Lifestyle Benefits
The Axis MyZone Credit Card gives you 15% off on dining bills (up to ₹500 per visit) at partner restaurants under the Axis Bank Dining Delights programme. Two such visits a month would translate to ₹1,000 in savings, which on its own is double the annual fee.
The dining discount works at over 4,000 partner restaurants across India and is applied at the time of bill payment. It cannot be combined with restaurant-side coupons or Zomato Pro discounts, but it stacks well with EDGE points (so you earn rewards on the discounted amount as well).
Fuel Surcharge Waiver
The Axis MyZone Credit Card offers a 1% fuel surcharge waiver on all fuel transactions in India, valid on transactions between ₹400 and ₹4,000. The maximum benefit is capped at ₹400 per statement cycle.
If you fill ₹3,000 of fuel a month, the 1% surcharge would have been ₹30, which is now waived. Over a year, that is ₹360 in saved surcharges. Note that fuel spends do not earn EDGE points on this card, so use a dedicated fuel card if your monthly fuel spend is heavy.
View FAQ
Commonly Asked Questions
How do I claim my Sony LIV Premium subscription?
The Sony LIV Premium voucher is sent to your registered email address within 30 to 60 days of your first transaction. You then redeem the code on the Sony LIV app or website by entering it under the subscription section. There is no minimum spend on the first transaction, so even a ₹100 swipe works.
What if I miss the 30-day window for the first transaction?
The Sony LIV welcome benefit is strictly tied to the 30-day window from card issuance. If you miss it, the offer lapses and cannot be claimed retroactively. Plan a small transaction (a Swiggy order or Amazon purchase) right after activation to make sure you do not lose the ₹1,499 benefit.
Is the Sony LIV subscription renewed every year?
The welcome benefit covers only the first year. Renewal of Sony LIV Premium in subsequent years is not bundled with the card and would need to be purchased separately. So plan your viewing accordingly in year one.
Can I use the Sony LIV subscription on multiple devices?
Sony LIV Premium allows simultaneous streaming on a limited number of devices as per the platform's standard plan terms. The voucher you receive does not change those rules, you simply get the subscription credited to your account.
How much is one EDGE Reward point worth in rupees?
One EDGE Reward point is worth ₹0.25 when redeemed against statement credit or vouchers on the EDGE Rewards portal. So 4,000 points equal ₹1,000 in spend value, which gives you a clear yardstick to measure your earn rate.
Do I earn EDGE points on every transaction?
You earn EDGE points on most retail transactions, but several categories are excluded. These include fuel, EMI conversions, wallet loads, rent payments, jewellery, government payments, utility bill payments, insurance, education spends, and cash advances. Plan your spends through the card mostly on shopping, dining, and travel to maximise points.
What is the milestone bonus on annual spends?
You earn an additional 1,000 EDGE Reward points when your annual spending crosses ₹1.5 lakh in a card anniversary year. That is ₹250 in extra value, which is also the threshold that waives your annual fee. Hit ₹1.5 lakh in spending and you essentially get the renewal year free plus 1,000 bonus points.
Do EDGE points expire?
EDGE Reward points on the Axis MyZone Credit Card expire after a period of 36 months from the date of accrual. Redeem your points on time through the EDGE Rewards portal so you do not lose unclaimed value.
Where can I redeem my EDGE points?
Points can be redeemed against statement credit, gift vouchers from popular brands, flight and hotel bookings, merchandise, and travel partner conversions on the EDGE Rewards portal at edgerewards.axisbank.com. Statement credit is the most efficient redemption since you do not lose value to brand-specific markups.
Can I redeem EDGE points for cash?
EDGE points cannot be redeemed for direct cash transfer to a bank account, but you can redeem them against your card statement, which has the same effect. A 4,000-point redemption knocks ₹1,000 off your outstanding bill.
What is the easiest way to maximise reward points on this card?
Concentrate your dining, shopping, and travel spends on this card and avoid swiping for fuel, rent, utilities, insurance, and education since those categories earn nothing. A focused user spending ₹20,000 a month in eligible categories earns roughly 4,800 EDGE points a year, worth ₹1,200 plus the ₹1,499 Sony LIV benefit.
Are reward points capped on this card?
The Axis MyZone Credit Card has no hard monthly cap on its base 4 points per ₹200 reward earning, so heavy spenders keep accruing at the same rate. The 1,000-point milestone bonus is a one-time annual reward triggered at the ₹1.5 lakh spend mark in each card anniversary year.
How many lounge visits do I get on the Axis MyZone Credit Card?
You get 1 complimentary domestic airport lounge access per calendar quarter, so a maximum of 4 visits a year. The benefit is for the primary cardholder only, and add-on cardholders are not covered under this perk.
What is the spend condition for the lounge benefit?
You need to spend at least ₹50,000 on the card in the previous 3 months for the lounge access benefit to be activated for the next quarter. Without this spend, your free quarterly visit will not be available even if you swipe the card at the lounge.
Is international lounge access available on this card?
The Axis MyZone Credit Card offers only domestic airport lounge access. International lounge access is not part of this card's benefits and is reserved for higher tier Axis cards like the Magnus or the Reserve.
Which lounges accept the Axis MyZone Credit Card?
The card grants access to a curated list of select domestic lounges at major Indian airports, mostly under the Visa lounge programme. The exact lounge list is updated by Axis Bank periodically and you can check it on the EDGE Rewards portal or directly at the lounge before swiping.
How does the MakeMyTrip Wednesday flight offer work?
You book a flight on MakeMyTrip on any Wednesday and pay using the Axis MyZone Credit Card to get up to 15% instant discount. The discount is applied at checkout and is subject to a maximum cap published by MakeMyTrip from time to time.
Is the discount applicable to international flights?
The Axis Bank Wednesday Delight offer covers domestic flight bookings on MakeMyTrip. International flight inclusions vary by current campaign terms, so check the offer page on MakeMyTrip before you book.
Can I combine the flight discount with my reward points?
Yes, you can apply the Wednesday discount during checkout and still earn EDGE Reward points on the final billed amount. So a ₹6,800 ticket after discount would earn you 136 EDGE points, worth ₹34 in additional value.
Are there any other travel perks on this card?
Beyond the MakeMyTrip Wednesday flight offer and the quarterly domestic lounge access, the Axis MyZone Credit Card does not offer dedicated bus, cab, or railway booking discounts. For a fuller travel-focused card, you would look at the Axis Vistara series or the Axis Atlas instead.
How does the Axis Bank Dining Delights offer work?
You enrol in the Axis Bank Dining Delights programme through the Axis Bank app or website, then pay your restaurant bill using the Axis MyZone Credit Card at any partner outlet to get 15% off, capped at ₹500 per visit. So a ₹3,500 bill would attract the maximum ₹500 discount.
Are food delivery apps like Swiggy and Zomato included?
The Axis Bank Dining Delights programme covers dine-in transactions at partner restaurants, not food delivery orders through Swiggy or Zomato. For food delivery savings, you would rely on bank-specific app offers or category cashback cards.
How many times can I use the dining offer?
The dining discount can be used multiple times in a month at participating restaurants, with each visit individually capped at ₹500. Frequent diners can extract ₹1,000 to ₹3,000 worth of savings every year through this benefit alone.
Do I earn EDGE points on dining transactions?
Yes, dining is an eligible category and you earn the standard 4 EDGE points per ₹200 spent. So a ₹2,000 restaurant bill earns you 40 EDGE points (₹10 in value) on top of the 15% Dining Delights discount.
Do I earn reward points on fuel transactions?
No, fuel is in the excluded categories list for EDGE Reward points on this card. You only get the 1% fuel surcharge waiver on transactions between ₹400 and ₹4,000, not the regular reward points.
Is the fuel waiver capped per cycle?
Yes, the fuel surcharge waiver is capped at ₹400 per statement cycle. That means the benefit kicks in on monthly fuel spending of around ₹40,000 before it caps out.
Does the fuel waiver work at all petrol pumps?
The 1% fuel surcharge waiver applies across all petrol pumps in India, regardless of brand, as long as the transaction is between ₹400 and ₹4,000. So it works at HPCL, IOCL, BPCL, Reliance, and Shell pumps.
What happens if my fuel transaction is below ₹400 or above ₹4,000?
Transactions outside the ₹400 to ₹4,000 band are not eligible for the fuel surcharge waiver. So break larger fuel fills into smaller transactions where possible to stay within the eligible window.

How to Redeem Rewards & Cashback?
Rewards Conversion Rate
1 reward point = ₹0.25

Redemption Options
- EDGE Rewards by Axis Bank
To check redemption catalogue
EDGE Reward points earned on the Axis MyZone Credit Card are redeemed through the Axis Bank EDGE Reward...
Read MoreRead Less
EDGE Reward points earned on the Axis MyZone Credit Card are redeemed through the Axis Bank EDGE Reward...
EDGE Reward points earned on the Axis MyZone Credit Card are redeemed through the Axis Bank EDGE Rewards portal at edgerewards.axisbank.com. The redemption flow is fully digital and the value of each point is fixed at ₹0.25 across most categories.
Step 1: Log in to the EDGE Rewards portal using your Axis Bank net banking credentials. Step 2: Navigate to the Redeem section and choose your category (statement credit, gift vouchers, merchandise, flight or hotel bookings, or partner conversions). Step 3: Select your item or amount, confirm with the OTP sent to your registered mobile, and the redemption is processed.
The most efficient redemption is statement credit, where each point converts at the full ₹0.25 value. Gift vouchers and merchandise sometimes have a slight markup, so you get less per point. Flight and hotel bookings on the EDGE travel portal offer competitive value if you can match dates and routes.
To put redemption in real numbers: if you accumulate 5,000 EDGE points (which is roughly what an active user with ₹2.5 lakh in annual spends would earn including the milestone bonus), your redemption value is ₹1,250 in statement credit. There is no fee on reward redemption on this card, so the full value goes to you.
Points expire 36 months after the date of accrual, so it is worth checking your point balance at least once a year and redeeming before any block of points lapses.
View FAQ
Commonly Asked Questions
How do I redeem EDGE Reward points?
Log in to edgerewards.axisbank.com, choose Redeem, pick your category (statement credit gives the best value), select your item or amount, confirm with OTP, and the redemption reflects in 3 to 7 working days.
Is there a minimum point balance for redemption?
The minimum redemption threshold varies by category. For statement credit, you need at least 1,000 points (worth ₹250). For most gift vouchers, the threshold starts at 200 points and goes up depending on the brand.
What is the rupee value of one EDGE point?
One EDGE Reward point is worth ₹0.25 when redeemed against statement credit. So 4,000 points equal ₹1,000. Other redemption categories may give slightly less per point depending on partner pricing.
Is there a fee for reward redemption on this card?
No, there is no fee for redeeming EDGE Reward points on the Axis MyZone Credit Card. You receive the full ₹0.25 per point in statement credit redemptions, with no deduction.
How long do EDGE Reward points stay valid?
EDGE Reward points expire 36 months from the date they were earned. Track your accrual dates in the EDGE portal and redeem the oldest points first to avoid lapses.
Can I transfer EDGE points to airline miles?
Yes, the EDGE Rewards portal supports point conversion to several airline frequent flyer programmes (like Vistara, Etihad, and Singapore Airlines KrisFlyer) at varying conversion ratios. Conversion rates are subject to change and the EDGE portal shows the current best rate at the time of redemption.

Gift card - Key Terms

Once you apply, we will start tracking your application
Generally takes 2-72 hrs

Once the bank confirms us of your successful card activation, we will process your rewards
Generally takes 7-75 days

You can then withdraw your rewards via Amazon Pay Balance/Flipkart gift cards
Generally takes 7-75 days
Note: If you currently hold or have ever held an Axis Credit Card, you are not eligible for CashKaro Rewards.
Rewards Related
- If you currently hold or have ever held an Axis Credit Card, you are not eligible for Gift Card
- A minimum transaction of Rs.100 within 30 days is mandatory to activate your card; otherwise, you wont be eligible for the Rewards
- Please use Aadhaar linked mobile number to fill the application
- If the distance between your residence and office addresses is 150 km or more, please ensure that your residence is selected as the mailing address. Applications not adhering to this will be rejected
- VKYC done over 50km from your Aadhaar/communication address will result in application rejection and loss of Rewards
Also, Remember
- Resume your application only via Great.Cards to avoid losing Rewards
- If your Rewards do not track, raise a Missing Rewards Ticket within 30 Days from the application date
- Rewards can only be redeemed as Amazon Pay Balance and Flipkart Gift Card

Bank Exclusions
You will not earn points / cashback on spends in the following categories
For Points / Cashback Earnings

Fuel Spends
EMI Spends
Wallet Loads
Jewellery Purchases
Cash Advances
Payment of outstanding balances
Bank Charges & Fees
Rent Payment
Government-related Transactions
Insurance Payments
Education Spends
Utility Bill Payments
For Spends Waiver
Fuel Spends
EMI Spends
Wallet Loads
Jewellery Purchases
Cash Advances
Payment of outstanding balances
Bank Charges & Fees
Rent Payment
Government-related Transactions
Insurance Payments
Education Spends
Utility Bill Payments
While the Axis MyZone Credit Card earns reward points across most retail categories, several spending c...
Read MoreRead Less
While the Axis MyZone Credit Card earns reward points across most retail categories, several spending c...
While the Axis MyZone Credit Card earns reward points across most retail categories, several spending categories are excluded from the EDGE Rewards programme. Knowing this list upfront helps you avoid the disappointment of zero points on what feels like a normal swipe.
The excluded categories on the Axis MyZone Credit Card are: fuel spends, EMI spends, wallet loads, jewellery purchases, cash advances, payment of outstanding balances, bank charges and fees, rent payment, government-related transactions, insurance payments, education spends, and utility bill payments.
Real-world impact: if your monthly spending is ₹30,000 and ₹10,000 of it goes to rent, utilities, and insurance, you lose out on 200 EDGE points (worth ₹50). Over a year, that is ₹600 in missed rewards. So while these spends still pass through the card, they do not contribute to your reward earnings or your ₹1.5 lakh annual fee waiver target.
What happens when a transaction falls under an excluded category? The transaction goes through normally, you get charged the regular billing, and you simply do not earn EDGE points on that amount. Some categories like rent payment and wallet loads also attract additional convenience fees on most credit cards, which is another reason to route them through UPI or direct net banking instead.
The Axis MyZone Credit Card does not impose a hard monthly cap on its base 4 EDGE points per ₹200 reward earning, which is one of its quiet wins compared to cards like SBI SimplyCLICK that cap online reward points at 10,000 per month.
View FAQ
Commonly Asked Questions
Do I earn EDGE points on rent payments?
No, rent payments are excluded from the EDGE Rewards programme on the Axis MyZone Credit Card. Plus, most rent payment apps charge a 1% to 1.5% convenience fee on credit card transactions, so you lose money on rent paid through cards.
Are utility bill payments eligible for rewards?
No, utility bills (electricity, water, broadband, mobile postpaid) are excluded from EDGE Rewards earning on this card. Use UPI or auto-debit from your savings account for utility bills since you save on convenience fees and do not lose any reward value.
Do EMI conversions earn reward points?
No, when you convert a transaction to EMI, the EMI portion stops earning EDGE points. The original purchase may have earned points at the time of the swipe, but the bank reverses the points once the EMI conversion is processed.
Why are insurance payments excluded?
Insurance premiums are excluded because the bank earns a much lower interchange fee on insurance MCC categories. The same logic applies to government payments, utility bills, and education fees, where merchant categories carry low interchange rates.
Are wallet top-ups excluded from rewards?
Yes, loading money into Paytm, PhonePe, MobiKwik, or other wallets does not earn EDGE points on the Axis MyZone Credit Card. The rationale is to prevent point farming through wallet recycling.
Do excluded transactions count towards the ₹1.5 lakh annual fee waiver?
No, transactions in excluded categories do not count towards the ₹1.5 lakh fee waiver threshold either. So plan your eligible spends across shopping, dining, and travel to clear the waiver.

Bank Fee Structure
| Structure | Details |
|---|---|
Forex Markups  3.5% forex markup is charged on transactions made in currencies other than INR. Applies to international POS payments and online purchases charged in foreign currency | 3.5% |
APR Fees Finance charges of 3.75% per month 45% per annum apply on unpaid outstanding balances until the amount is fully repaid | 3.75% |
ATM withdrawal 2.5% of the withdrawn amount is charged on cash advances using the credit card minimum ₹500, if applicable | 2.5% |
Reward Redemption Fees No fee is charged when redeeming reward points on this card | Not Applicable |
Link for all T&Cs | Click Here |
Railway Surcharge A surcharge of 1% is applied to transactions made for booking railway tickets | 1% |
Rent Payment Fees A surcharge fee of 1% applies on rental transactions made using the credit card | 1% |
cheque Payment Fees A fee of 2% of the payment amount, subject to a minimum of ₹500, is levied for cheque return, cheque dishonour, or auto-debit reversal | 2% |
Cash Payment Fees A fee of ₹175 is levied on cash payments made towards the credit card at an Axis Bank branch | ₹175 |
| Late Payment Fees | Amount Due |
|---|---|
| ₹0 - ₹500 | ₹0 |
| ₹501 - ₹5000 | ₹500 |
| ₹5001 - ₹10000 | ₹750 |
| Above ₹10000 | ₹1200 |
The Axis MyZone Credit Card sits in the standard fee bracket for Indian entry-level lifestyle cards. No...
Read MoreRead Less
The Axis MyZone Credit Card sits in the standard fee bracket for Indian entry-level lifestyle cards. No...
The Axis MyZone Credit Card sits in the standard fee bracket for Indian entry-level lifestyle cards. None of the fees are unusually high, but a few are worth understanding before you swipe. Here is a fee-by-fee breakdown with practical rupee examples so you know what to expect on your statement.
Joining Fee: The joining fee is ₹500 plus 18% GST, so a total of ₹590 hits your statement at the time of card issuance. The fee is not directly offset by any cashback or credit, but the welcome benefit (Sony LIV Premium worth ₹1,499) more than covers it. Axis Bank does run Lifetime Free promotions on this card through certain channels and partner bundles.
Annual or Renewal Fee: The annual fee is also ₹500 plus 18% GST, billed on your first card anniversary. The fee is fully waived if you spend ₹1.5 lakh or more in the previous card year. Practical example: spending ₹12,500 a month on this card across shopping, dining, and travel takes you past the ₹1.5 lakh threshold and triggers an automatic fee reversal in your renewal statement.
APR or Interest Rate: The APR is 3.50% per month (about 42% annualised) when carried on rolled-over balances. Credit cards offer an interest-free period of 20 to 55 days, but missing your due date triggers interest from the original transaction date. Practical example: if you carry an unpaid balance of ₹10,000 for one month, the interest charged is roughly ₹350. To avoid heavy interest, convert large purchases to EMIs (where standard rates are around 16% per annum) instead of paying minimum due. Failing to pay even the EMI on time can push the effective annual interest closer to 42%.
Late Payment Charges: Late payment fees follow a slab-based structure. ₹0 for outstanding up to ₹500, ₹400 for ₹501 to ₹1,000, ₹750 for ₹1,001 to ₹10,000, ₹950 for ₹10,001 to ₹25,000, ₹1,100 for ₹25,001 to ₹50,000, and ₹1,300 for outstanding above ₹50,000. Practical example: if your minimum due is ₹3,000 and you miss the payment, the late fee charged is ₹750. Additionally, if you miss the minimum amount due for two consecutive cycles, an extra ₹100 late payment charge applies every cycle until you clear the dues.
Foreign Transaction or Forex Markup Fee: The forex markup is 3.50% on every transaction made in a non-INR currency. This applies to both international POS swipes and online purchases billed in foreign currency. Practical example: a USD 100 hotel deposit abroad (roughly ₹8,300 at current INR rates) attracts a forex markup of ₹290.50, bringing your final billed amount to about ₹8,590 plus GST on the markup. So international swipes can quietly inflate your bill by 3.5% to 4%.
ATM Cash Withdrawal Fee: ATM cash withdrawal on the credit card attracts a fee of 2.50% of the withdrawn amount, with a minimum charge of ₹500 (where applicable). Plus, interest at 3.50% per month starts accruing from the day of withdrawal, with no interest-free grace period. Practical example: withdrawing ₹10,000 in cash on the credit card costs you ₹500 in cash advance fee upfront plus ₹350 in monthly interest, so even one month of unpaid balance costs ₹850 on a ₹10,000 withdrawal. Avoid cash withdrawals on credit cards entirely unless it is an absolute emergency.
Rent Payment Convenience Fee: Axis Bank itself does not levy a card-side rent payment fee on the Axis MyZone Credit Card, but third-party rent payment platforms (like CRED, NoBroker, or Magicbricks) charge 1% to 1.5% of the rent amount on credit card transactions. Combined with the fact that rent payments do not earn EDGE Reward points on this card, paying rent through this card is not worth it.
Railway Surcharge: Railway booking and cancellation charges on this card are levied as prescribed by IRCTC or Indian Railways from time to time. The exact charge depends on the booking platform and ticket category, with standard IRCTC convenience fees ranging from ₹15 to ₹30 per booking.
Cash Payment Fee: If you pay your credit card bill in cash at an Axis Bank branch, a fee of ₹250 plus applicable taxes is charged on each transaction. Practical example: paying a ₹25,000 bill in cash costs you an extra ₹295 (₹250 plus 18% GST). Always use UPI, NEFT, or auto-debit to avoid this charge.
Cheque Payment Fee: Bill payment by cheque attracts a fee of ₹100 plus applicable taxes per transaction. So a single cheque payment costs ₹118 inclusive of GST. Cheque payments also take 2 to 3 working days to clear, so if your due date is close, the late payment risk is high.
Reward Redemption Fee: There is no fee for redeeming EDGE Reward points on this card. The full ₹0.25 per point value flows to you in statement credit, gift vouchers, or other redemption categories. This is one of the quiet wins of the Axis MyZone Credit Card compared to cards like the SBI SimplyCLICK that charge ₹99 per redemption.
Below is a consolidated summary of all fees on the Axis MyZone Credit Card. The amounts are exclusive of GST unless explicitly stated.
| Fee Type | Amount |
|---|---|
| Joining Fee | ₹500 |
| Annual Fee | ₹500 (waived on ₹1.5 lakh annual spend) |
| APR (Monthly Interest) | 3.50% per month |
| Late Payment Fee | ₹0 to ₹1,300 (slab based) |
| Forex Markup | 3.50% |
| ATM Cash Withdrawal Fee | 2.50% of withdrawn amount (min ₹500) |
| Rent Payment Convenience Fee | Levied by third-party platforms (1% to 1.5%) |
| Railway Surcharge | As prescribed by IRCTC or Indian Railways |
| Cash Payment Fee | ₹250 plus taxes |
| Cheque Payment Fee | ₹100 plus taxes |
| Reward Redemption Fee | Not Applicable |
View FAQ
Commonly Asked Questions
What is the interest rate on the Axis MyZone Credit Card?
The monthly interest rate is 3.50%, which works out to approximately 42% annualised on rolled-over balances. Pay your bill in full every month to avoid this charge.
How much is the late payment charge?
Late payment fees range from ₹0 (for outstanding up to ₹500) to ₹1,300 (for outstanding above ₹50,000), based on the slab of your unpaid amount. Missing the minimum due for two consecutive cycles also adds an extra ₹100 charge per cycle until cleared.
What is the forex markup on this card?
The forex markup is 3.50% on all non-INR transactions. So a ₹10,000 international purchase attracts ₹350 in markup, plus 18% GST on the markup itself. Forex markup makes this card unsuitable as a primary travel card for overseas use.
Is there a fee for ATM withdrawals?
Yes, ATM withdrawals on the credit card attract a 2.50% cash advance fee (minimum ₹500), plus 3.50% monthly interest from the day of withdrawal. Cash withdrawal on credit cards is one of the most expensive moves you can make and should be avoided.
Are there charges for paying my bill in cash or cheque?
Yes, paying your bill in cash at an Axis Bank branch costs ₹250 plus taxes per transaction, and cheque payments cost ₹100 plus taxes. Use UPI, NEFT, RTGS, or auto-debit instead since they are free and instant.
Is there a railway booking surcharge?
Railway booking and cancellation charges are levied as prescribed by IRCTC or Indian Railways. The standard IRCTC convenience fee for credit card payments is around ₹30 per booking, which is the same on most cards.
Are reward redemption fees applicable?
No, the Axis MyZone Credit Card does not charge a fee for redeeming EDGE Reward points. The full ₹0.25 per point value reaches your statement credit or voucher, with no deduction.
Are there any over-limit charges?
Yes, transactions that exceed your assigned credit limit attract over-limit fees. Axis Bank charges 2.5% of the over-limit amount, subject to a minimum charge of ₹500. Always track your available limit on the Axis Bank app to avoid this.
What happens if I pay only the minimum amount due?
Paying only the minimum amount due (5% of the outstanding balance) avoids the late payment fee, but interest at 3.50% per month starts accruing on your remaining balance from the original transaction date. So minimum payment is a short-term fix, not a long-term plan.
Can I get an EMI conversion on big-ticket purchases?
Yes, Axis Bank offers EMI conversion on transactions of ₹2,500 and above, with tenures from 3 to 24 months. EMI interest rates start around 16% per annum, which is significantly cheaper than the regular 42% APR on rolled-over balances.
Is GST charged on credit card fees?
Yes, 18% GST is charged on all credit card fees and charges, including the joining fee, annual fee, late payment fee, forex markup, and cash advance fee. Factor this into your math when calculating the actual cost of any fee on your statement.
What is the minimum amount due each month?
The minimum amount due is set at 5% of the outstanding balance, subject to a minimum of ₹100 plus any unpaid amount from previous cycles, EMI dues, and over-limit charges. Pay the full statement amount whenever possible to avoid interest costs.

Documents Required
Axis Bank requires a standard set of KYC and income proof documents during the Axis MyZone Credit Card application. Keep digital copies ready before you start the application to make the process smooth.
Required documents for salaried applicants: PAN card, Aadhaar card, latest 3 months of salary slips, latest 6 months of bank statements showing salary credits, and a passport-size photograph. Fresh hires also submit their Form 16 or appointment letter as additional income proof.
Required documents for self-employed applicants: PAN card, Aadhaar card, latest 2 years of ITR, latest 6 months of business bank statements, GST registration certificate (where applicable), and proof of business existence (like a partnership deed, Udyam certificate, or business registration document).
NRIs are not eligible for the standard Axis MyZone Credit Card. Address proof can be the Aadhaar card itself, or alternative documents like a passport, voter ID, driving licence, or a recent utility bill (not older than 3 months).
View FAQ
Commonly Asked Questions
Is a PAN card mandatory for the Axis MyZone Credit Card?
Yes, PAN card is mandatory for all Indian credit card applications since it is needed for KYC, credit bureau pulls, and tax reporting. Applications without PAN are not processed.
Can I apply without a salary slip?
Salaried applicants need to submit salary slips. If you do not have salary slips (for example, if you are a fresh hire), you can submit your appointment letter and bank statements showing the salary credit instead.
Do I need to submit a photograph during application?
For online applications with Video KYC, the system captures your photograph during the KYC video call, so you do not need to upload a separate photograph. Offline applications may require one passport-size photograph.
What address proof is accepted?
Aadhaar card is the most widely accepted address proof. Other accepted documents include passport, voter ID, driving licence, utility bills not older than 3 months, and registered rent agreements.
Can I use a digital Aadhaar for application?
Yes, Axis Bank accepts digitally signed Aadhaar (e-Aadhaar) downloads from the UIDAI portal. The bank verifies the QR code on the digital Aadhaar during KYC, so you do not need a physical copy.
How long are the bank statement requirements?
Axis Bank requires the latest 6 months of bank statements for salaried applicants, showing regular salary credits. Self-employed applicants need 6 months of business bank statements plus 2 years of ITR.

Credit Limit and What to Expect
Axis Bank sets the credit limit on the Axis MyZone Credit Card individually for each applicant, based on your income, credit bureau profile, existing obligations, and overall banking relationship. There is no fixed published number.
For a salaried applicant earning ₹25,000 to ₹40,000 a month, the starting credit limit sits between ₹40,000 and ₹1,20,000. Higher income brackets (₹50,000 plus monthly) often see opening limits between ₹1.5 lakh and ₹3 lakh. Self-employed applicants with strong ITR-backed income and good CIBIL scores fall into similar limit ranges.
Axis Bank reviews your card usage every 6 to 12 months and offers limit enhancements if you have used the card consistently, paid your bills on time, and your credit score has improved. Limit enhancement is also offered on request if you can show a higher income (a recent salary hike, for example) with supporting documents.
View FAQ
Commonly Asked Questions
What is the starting credit limit on the Axis MyZone Credit Card?
For a salaried applicant earning ₹25,000 to ₹40,000 a month, the typical opening credit limit ranges from ₹40,000 to ₹1.2 lakh. Limits scale upwards based on your declared income, CIBIL score, and existing relationship with Axis Bank.
How can I increase my credit limit?
You can request a limit enhancement after 6 to 12 months of consistent card usage and timely payments. Submit your latest 3 months of salary slips or revised ITR, along with a written request through net banking or the Axis Bank app.
Will using the full credit limit hurt my credit score?
Using more than 30% of your credit limit consistently can lower your CIBIL score, even if you pay the bill in full. So if your limit is ₹1 lakh, try to keep your monthly statement balance under ₹30,000 to maintain a healthy credit utilisation ratio.
Can I get a temporary credit limit increase?
Axis Bank offers temporary credit limit increases for short-term, large-ticket spends (like booking a vacation or purchasing electronics). You can request this through customer care or the app, and it stays valid for 30 to 90 days.
What is the cash withdrawal limit on this card?
The cash withdrawal limit is set at 20% to 40% of your total credit limit. So a ₹1 lakh limit allows you to withdraw between ₹20,000 and ₹40,000 in cash, although ATM withdrawal carries a 2.50% fee plus monthly interest at 3.50%, making it an expensive option.
How often does Axis Bank review credit limits?
Axis Bank conducts a portfolio review every 6 to 12 months and offers automatic limit enhancements to qualifying cardholders. You can also request a manual review with updated income proof at any time after 6 months of card activity.

How to Apply?
Applying for the Axis MyZone Credit Card is straightforward and largely digital. Most salaried applicants get a decision within 24 to 72 hours, and physical card delivery takes 5 to 10 working days from the approval date.
The online route is the simplest. Visit the Axis Bank credit card section on the official website or app, choose the Axis MyZone Credit Card, and click on Apply Now. You fill in your basic details (name, mobile, PAN, date of birth, employment type, monthly income, and current city), upload soft copies of your KYC documents, and complete a Video KYC if you are not already an Axis Bank customer.
The offline route involves visiting an Axis Bank branch with physical copies of your documents. This is rarely needed unless you are an existing Axis Bank customer and prefer in-person service.
Once you submit the application, Axis Bank runs a credit bureau pull, verifies your KYC, and either issues a digital approval or asks for additional documents. After approval, the physical card is shipped to your registered address along with a welcome kit and a separate PIN mailer.
Application status can be tracked online using your application reference number and registered mobile number on the Axis Bank credit card status portal.
View FAQ
Commonly Asked Questions
How do I apply for the Axis MyZone Credit Card online?
Go to the Axis Bank website, navigate to Credit Cards, select Axis MyZone, click Apply Now, fill the form, upload your KYC documents, and complete Video KYC. The whole process takes 15 to 20 minutes if your documents are ready.
How long does it take to get the card after applying?
Approval is granted within 24 to 72 hours of a complete application. The physical card is delivered within 5 to 10 working days from approval, and the PIN arrives separately.
Is Video KYC mandatory for the Axis MyZone Credit Card?
Video KYC is required for new-to-bank customers. If you already have an Axis Bank account with completed KYC, the bank can use your existing records and skip Video KYC for the credit card.
Can I track my application status online?
Yes, Axis Bank provides an online application tracker on its credit card website. You enter your application reference number along with your registered mobile and date of birth to view real-time status updates.
What happens if my application is rejected?
If your application is declined, Axis Bank intimates you by SMS or email. The most common reasons are a low CIBIL score, recent missed payments on existing loans, or insufficient income proof. You can reapply after 90 days once the underlying issue is fixed.
Will applying for this card affect my credit score?
The bank does a hard pull on your credit bureau report during application, which can dip your score by 5 to 10 points temporarily. Once the card is active and you start making timely payments, your score recovers and benefits from the additional credit line in 3 to 6 months.

That’s the full story of this credit card
Like this card? Your apply button’s just there.
Top Benefits


Apply and get ₹1400 Rewards
Top Benefits
Get Movie Ticket Free on Your Second District Booking with Coupon AXIS200
capped at ₹200 per month and with no reward points on movie transactions
Get ₹120 Off on Swiggy Orders With Coupon AXIS120
on minimum spends of ₹500, capped at ₹120 per order and redeemable up to 2 times a month per user

The smartest way to find your great credit card


We value your time and privacy. Your details stay secure and are used only to help you.
Company
We value your time and privacy. Your details stay secure and are used only to help you.