
IDFC
IDFC FIRST POWER Credit Card
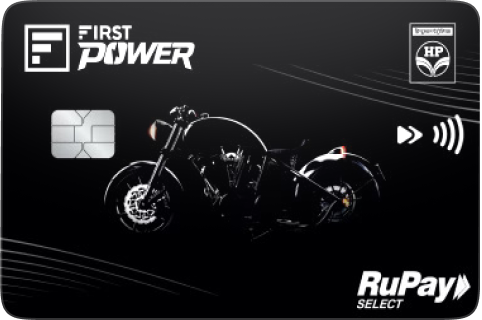
 This is an invite only card


Apply and get ₹750 Rewards

Top Benefits

Get Fuel Welcome Cashback on the first HPCL fuel
transaction of ₹250 or more within 30 days of card setup as ₹250 cashback
5% Cashback on First EMI Conversion
get 5% cashback up to ₹1,000 on converting the first transaction to EMI

Best For
Fuel

Shopping
Grocery Shopping

Travel
Utility Bills

The IDFC FIRST Power Credit Card is a targeted, utility-focused RuPay card designed specifically for ev...
Read More Read Less

The IDFC FIRST Power Credit Card is a targeted, utility-focused RuPay card designed specifically for ev...
The IDFC FIRST Power Credit Card is a targeted, utility-focused RuPay card designed specifically for everyday commuters and budget-conscious households. If you frequently fill up your tank at HPCL fuel stations, buy groceries for your home, and pay monthly utility bills, this card turns those routine expenses into tangible savings. With a highly accessible joining fee of just Rs. 199, it offers up to 5% savings on HPCL fuel purchases when combined with the HP Pay App.
What sets this card apart from generic cashback options is its hyper-focus on specific spending categories. While many entry-level cards offer flat 1% returns, the IDFC FIRST Power Credit Card accelerates your rewards to 2.5% for groceries, utilities, and FASTag recharges. The bank estimates that an average user maximizing these specific categories can save around Rs. 7,658 annually. This card works best for users who want to extract maximum value from their necessary monthly household and transit budgets without paying premium annual fees.
View FAQ
Commonly Asked Questions
Is the IDFC FIRST Power Credit Card lifetime free?


No, the card comes with a joining fee of Rs. 199 plus GST and an annual fee of Rs. 199 plus GST. However, you can get the annual fee waived if you spend Rs. 50,000 or more in the previous year.
Is this a good credit card for beginners?
Yes, with an accessible minimum income requirement of Rs. 25,000 per month and a low annual fee, it serves as a highly practical first card. The benefits target everyday necessities like fuel and groceries, making it easy to earn rewards without changing your normal spending habits.
Who should apply for this card?
Commuters who regularly use HPCL petrol pumps and households looking to save money on groceries and electricity bills should apply. If your monthly fuel and grocery bill crosses Rs. 5,000, this card easily pays for itself.
What network does this card use?
This card is issued on the RuPay network. This allows you to link your credit card to UPI apps for scanning and paying at merchant QR codes, adding significant convenience to your daily shopping.

Expert Review
In my experience analyzing dozens of entry-level credit cards, the IDFC FIRST Power Credit Card stands out for knowing exactly what it wants to be. It is not trying to sell you a luxury lifestyle; it is selling you a cheaper commute and lower grocery bills. At Rs. 199, the pricing is highly aggressive, making the Rs. 50,000 annual fee waiver target extremely achievable for middle-class households.
The 5% total return on HPCL fuel and the 2.5% return on groceries and utilities are fantastic value points that directly combat everyday inflation. However, the card has a glaring weakness: its base reward rate. Offering a mere 0.33% (2 points per Rs. 150) on general spends is incredibly low. Furthermore, by excluding the accelerated categories (fuel, groceries, utilities) from base earnings entirely, the card penalizes you once you cross the monthly caps.
My verdict? Keep this card in your car's sun visor. Use it strictly for HPCL fuel, your monthly electricity bill, and household groceries until you hit the monthly caps. For dining, electronics, and online shopping, pair this with a flat-rate cashback card to ensure you are maximizing value across the board.

Joining / Annual Fee
Joining Fees
₹235 ( ₹199 + GST )

Annual Fees
₹235 ( ₹199 + GST )
The fee structure of the IDFC FIRST Power Credit Card is designed to be low-risk and easily waivable fo...
Read MoreRead Less
The fee structure of the IDFC FIRST Power Credit Card is designed to be low-risk and easily waivable fo...
The fee structure of the IDFC FIRST Power Credit Card is designed to be low-risk and easily waivable for regular users. Understanding these costs ensures you do not pay unnecessary charges.
To activate your account, you must pay a one-time joining fee of Rs. 199 plus applicable GST. This fee is instantly offset if you utilize the welcome benefit voucher worth Rs. 250 at HPCL. Furthermore, this joining fee gets completely reversed if you spend Rs. 50,000 during your anniversary year.
From the second year onward, the bank charges a recurring annual fee of Rs. 199 plus GST. However, avoiding this fee is very manageable. The annual fee is waived if you spend Rs. 50,000 or more on your card in the previous year. Breaking the math down: to hit Rs. 50,000 a year, you only need to spend about Rs. 4,167 per month. Since this card is tailored for household utilities and fuel, routing just your monthly petrol and electricity bills through the card will effortlessly clear the waiver threshold.
View FAQ
Commonly Asked Questions
What are the joining fees for this card?
The one-time joining fee is Rs. 199 plus applicable GST, required for card activation.
Can the joining fee be waived?
Yes, the joining fee is reversed if you achieve card spends of Rs. 50,000 during your first anniversary year.
Is there a welcome bonus to offset the joining fee?
Yes, making a fuel transaction of Rs. 250 or more at an HPCL station within 60 days gives you a Rs. 250 voucher, which covers the cost of the joining fee.
What is the annual or renewal fee?
From the second year onwards, an annual fee of Rs. 199 plus GST is charged to your statement.
Is there an annual fee waiver option?
Yes, you can get the annual fee waived by meeting a total spend of Rs. 50,000 or more in the preceding year.
What is the spending requirement for the annual fee waiver?
You need to spend Rs. 50,000 annually. For instance, spending just Rs. 4,167 a month on fuel and groceries guarantees your next year's fee is waived.
Is the fee waiver based on the calendar year or card anniversary year?
The spending threshold is calculated based on your card anniversary year, tracking from the date your card was issued.
What happens if I don't meet the fee waiver spending requirement?
If you fall short of the Rs. 50,000 threshold, the Rs. 199 plus GST fee will automatically be applied to your credit card bill on the renewal month.

Eligibility
Age
Criteria*
21-60 years
Salary
Criteria*
3LPA
Credit
Rating*
720+
New to credit
allowed
Yes
Existing Bank
Customer Allowed
Yes
Applying for the IDFC FIRST Power Credit Card requires meeting a straightforward set of age, income, an...
Read MoreRead Less
Applying for the IDFC FIRST Power Credit Card requires meeting a straightforward set of age, income, an...
Applying for the IDFC FIRST Power Credit Card requires meeting a straightforward set of age, income, and credit score parameters. The bank has kept the barriers to entry relatively low, making it accessible to a large portion of the working population.
The primary cardholder must be between 21 and 60 years of age. Whether you draw a monthly salary or run your own business, both employment types are welcome to apply. If you are salaried, you need a minimum monthly income of Rs. 25,000. That means an entry-level professional earning Rs. 3 Lakhs annually easily qualifies. For self-employed individuals, the requirement is the same: you must show an Income Tax Return (ITR) of at least Rs. 3 Lakhs per annum.
Your credit history plays a vital role in the approval process. The bank explicitly recommends a CRIF or CIBIL credit score of 720 or higher. Having a score of 720+ shows you have a history of paying loans or other credit card bills on time, ensuring a smooth application journey.
View FAQ
Commonly Asked Questions
What is the minimum age to apply for this card?
The primary cardholder must be at least 21 years old to be eligible for this credit card.
What is the maximum age limit for the primary cardholder?
The upper age limit for eligibility is 60 years at the time of submitting your application.
What is the minimum salary required for salaried applicants?
Salaried individuals need a minimum monthly income of Rs. 25,000 to qualify. For example, earning exactly Rs. 3 lakh annually makes you eligible.
What is the minimum annual income for self-employed applicants?
Self-employed professionals and business owners must demonstrate an annual income of at least Rs. 3 Lakhs per annum through their ITR filings.
Can self-employed individuals apply for this card?
Yes, both salaried and self-employed professionals can apply as long as they meet the respective income and documentation requirements.
What credit score is needed for approval?
A good credit score of 720+ on bureaus like CRIF or CIBIL is recommended by the bank for smooth approval.
Will my application be rejected if my credit score is below 720?
While a score below 720 increases rejection chances, the bank considers multiple factors including your income level, current debt, and existing banking relationships.
Can students apply for this credit card?
Students without a regular income stream of Rs. 25,000 per month or an ITR of Rs. 3 Lakhs generally will not meet the eligibility criteria for this specific unsecured card.

All Card Benefits
- 3.5% savings on fuel spends: 21 rewards points per Rs. 150 spent on HPCL fuel, up to 700 rewards in a statement cycle
- 1.5% savings through HP Pay App: 6 Happy Coins per Rs. 100 on fuel spends through HP Pay App, up to 600 Happy Coins per month
- 2.5% savings On Grocery & Utility Spends: 15 reward points per ₹150 spent, up to 400 rewards per statement cycle
- 2.5% savings on IDFC FIRST FASTag Recharge: via HPCL Power card as 15 reward points per ₹150 spent, up to 200 rewards per statement cycle
- Up to 8.67% savings on travel spends: 52 reward points per ₹150 spent on hotels and 32 points per ₹150 spent on flights through Travel & Shop section on IDFC FIRST Mobile App
Welcome Benefits
The card offsets its own joining fee immediately through a practical welcome bonus....
Read MoreRead Less
Welcome Benefits The card offsets its own joining fee immediately through a practical welcome bonus....
Welcome Benefits
The card offsets its own joining fee immediately through a practical welcome bonus. When you receive your card, you have a 60-day window to make your first fuel purchase at an HPCL station. If that transaction is Rs. 250 or more, the bank rewards you with a gift voucher worth Rs. 250. For example, if you pay the Rs. 199 joining fee and spend Rs. 300 on petrol during your first week, you get a Rs. 250 voucher back, effectively putting you in profit from day one.
HPCL Fuel Savings
Fuel is where this card flexes its primary muscle. You earn a 3.5% savings rate on HPCL fuel spends. The bank calculates this as 21 reward points per Rs. 150 spent. You can earn a maximum of 700 reward points in a single statement cycle from this category. For example, if you spend Rs. 5,000 on HPCL fuel in a month, you hit the 700-point cap, which equals Rs. 175 in value.
You can boost this further by paying through the HP Pay App, which adds an extra 1.5% savings in the form of 6 Happy Coins per Rs. 100 spent. This is capped at 600 Happy Coins per month. Combined, you get an effective 5% return on your petrol or diesel expenses.
Grocery, Utility, and FASTag Benefits
Beyond the pump, the card helps manage household inflation. You get a 2.5% savings rate on grocery and utility bills. This is credited as 15 reward points per Rs. 150 spent, with a cap of 400 reward points per statement cycle. For example, spending Rs. 4,000 on electricity bills and supermarket runs will max out this cap, earning you Rs. 100 in points value.
Similarly, recharging your IDFC FIRST FASTag using this card yields 2.5% savings (15 points per Rs. 150), capped at 200 reward points per cycle. If you recharge your FASTag with Rs. 2,000, you will hit this limit and earn Rs. 50 in points.
Travel Perks and Insurance Coverage
While not a premium travel card, it offers decent incentives if you book through the bank's portal. You earn up to 8.67% savings on travel spends when using the Travel & Shop section of the IDFC FIRST Mobile App. Specifically, you get 52 reward points per Rs. 150 on hotels and 32 points per Rs. 150 on flights. Booking a Rs. 6,000 hotel room this way nets you 2,080 points, worth Rs. 520.
On the road, the card provides complimentary roadside assistance worth Rs. 1,399, up to 4 times a year. It also includes a personal accident cover of Rs. 2 lakh and lost card liability coverage up to Rs. 25,000.
Reward Points Structure
For any regular purchases outside the special categories, the card offers an uncapped base earning rate. You get 2 reward points for every Rs. 150 spent. Since each point is valued at Rs. 0.25, this results in a base reward rate of 0.33%. If you spend Rs. 15,000 on clothing or electronics, you earn 200 base points, which equals Rs. 50 in value. While the base rate is low, it remains uncapped, meaning high-ticket general spends will continuously accrue points without a monthly ceiling.
View FAQ
Commonly Asked Questions
How do I qualify for the welcome bonus?
You must complete your first fuel transaction of Rs. 250 or above at an HPCL fuel station. This transaction needs to happen within 60 days of your card setup to qualify for the voucher.
What is the exact value of the welcome benefit?
The welcome benefit is a gift voucher worth Rs. 250. This completely offsets your initial joining fee of Rs. 199.
When will I receive the welcome voucher after my fuel transaction?
The welcome voucher is delivered via SMS or email to your registered contact details within 30 days of the qualifying transaction settling.
Does a grocery purchase trigger the welcome bonus?
No, the welcome bonus specifically requires a fuel transaction at an HPCL fuel station. Spending Rs. 250 at a supermarket will not trigger this benefit.
How many points do I get for fuel purchases?
You earn 21 reward points for every Rs. 150 spent on fuel at HPCL stations. Since each point is worth Rs. 0.25, this translates to exactly 3.5% in savings.
Is there a limit on how much I can earn on fuel?
Yes, the 3.5% reward rate is capped at 700 reward points per statement cycle. This means once you spend Rs. 5,000 on fuel in a month, you will not earn the accelerated 21 points per Rs. 150 for additional fuel purchases.
Do I get fuel benefits at IndianOil or Bharat Petroleum?
No, these accelerated reward points are strictly tied to HPCL fuel stations. Transactions at other fuel brands fall under general exclusions and will not earn these specific rewards.
What are Happy Coins and how do I earn them?
Happy Coins are rewards issued by the HP Pay App. By linking your card to the app and paying for fuel, you earn 6 Happy Coins per Rs. 100 spent, capped at 600 coins per month.
Does the card offer a standard fuel surcharge waiver?
This card does not offer a standard fuel surcharge waiver benefit outside of its specific 3.5% reward structure for HPCL and the HP Pay app integration.
How much do I save on electricity and water bills?
You earn 15 points per Rs. 150 spent on utilities, which is a 2.5% return. If your electricity bill is Rs. 3,000, you earn 300 points worth Rs. 75.
What is the maximum I can earn on groceries and utilities?
You can earn up to 400 reward points per billing cycle combined across groceries and utilities. You hit this maximum after spending Rs. 4,000 in these categories.
Does any FASTag recharge earn the 2.5% reward?
No, the 2.5% savings specifically applies when you recharge an IDFC FIRST FASTag. Recharging FASTags issued by other banks will not earn these accelerated rewards.
What happens if I spend Rs. 6,000 on groceries in a month?
You will earn the accelerated 15 points per Rs. 150 on the first Rs. 4,000 spent, hitting the 400-point cap. The remaining Rs. 2,000 will not earn accelerated rewards because grocery spends are excluded from the card's base earning structure.
Do I earn 8.67% on all hotel bookings?
No, to get 52 reward points per Rs. 150 spent (which equals 8.67%), you must book your hotels exclusively through the Travel & Shop section on the IDFC FIRST Mobile App.
How much do I earn on flight tickets?
You earn 32 reward points per Rs. 150 spent on flights, provided you book through the bank's designated Travel & Shop app section. For a Rs. 15,000 flight ticket, you earn 3,200 points.
What does the roadside assistance cover?
The card offers roadside assistance worth Rs. 1,399, available up to 4 times a year. Services include emergency towing, on-site minor repairs, battery jump-starts, and fuel delivery.
Is there any airport lounge access included?
No, this card does not offer any complimentary airport or railway lounge access benefits.
How does the lost card liability work?
If you lose your card, you are protected against fraudulent transactions up to Rs. 25,000. You must report the loss to the bank immediately to activate this coverage.
What is the standard reward rate on this card?
You earn 2 reward points for every Rs. 150 spent on eligible base transactions. This translates to an effective reward rate of 0.33% on your general card spends.
What is the value of 1 reward point in rupees?
Each reward point is valued at Rs. 0.25. This means 4 points equal Rs. 1, making it straightforward to calculate your total cashback equivalent.
How many reward points do I earn per Rs. 100 spent?
The bank calculates rewards per Rs. 150. For an exact Rs. 150 purchase, you get 2 points. Transactions below Rs. 150 do not earn reward points, as points are calculated in multiples of the Rs. 150 spend threshold.
Is there a limit to how many base reward points I can earn?
No, the base earning rate of 2 points per Rs. 150 is completely uncapped. You will earn these points on all eligible general transactions regardless of your monthly spend volume.
Do I earn base points on fuel purchases?
No, fuel spends are explicitly excluded from base reward earnings. You only earn rewards on fuel through the specific 3.5% HPCL category benefit up to its cap.
Do I earn base points on grocery purchases?
No, grocery spends are excluded from base earning. You earn the accelerated 2.5% rate up to the 400-point limit, but beyond that, groceries do not earn the 2 base points per Rs. 150.
Which transactions are completely excluded from earning any reward points?
Insurance premium payments, EMI transactions, ATM cash withdrawals, and general utility bills are excluded from base reward earnings.
Do I earn points when paying rent?
Rent payments do not earn reward points and attract a 1% convenience fee, as they are excluded from the card's reward structure.
Do my reward points expire?
IDFC FIRST reward points never expire, allowing you to accumulate and redeem them whenever you choose without the pressure of a deadline.
How can I track my accumulated reward points?
You can view your real-time reward point balance by logging into the IDFC FIRST Mobile App or your net banking dashboard.

How to Redeem Rewards & Cashback?
Rewards Conversion Rate
1 reward point = ₹0.25

Redemption Options
- Flights & hotels Booking
- Gift vouchers
- Offline merchants
To check redemption catalogue
Accumulating points is only half the journey; redeeming them efficiently dictates the real value of you...
Read MoreRead Less
Accumulating points is only half the journey; redeeming them efficiently dictates the real value of you...
Accumulating points is only half the journey; redeeming them efficiently dictates the real value of your card. The IDFC FIRST Power Credit Card offers a highly flexible redemption process centralized through the IDFC FIRST Mobile App. You can also visit the official portal at https://firstrewards.in/ to explore the redemption catalogue.
Every single reward point you earn is worth exactly Rs. 0.25. The platform allows you to use your points for a wide array of options including flight bookings, hotel reservations, gift vouchers, and exclusive memberships. The most impressive feature is the ability to redeem points instantly online or at select offline partner merchants. When booking travel through their portal, you can pay up to 70% of your total booking amount using just your reward points. For example, if you are booking a Rs. 10,000 flight and have 20,000 points saved up, you can instantly apply those points to cover Rs. 5,000 of the ticket cost, paying the rest with your card.
View FAQ
Commonly Asked Questions
How do I redeem the reward points I have earned?
You can redeem your reward points directly via the IDFC FIRST Mobile App or by visiting the official rewards catalogue at https://firstrewards.in/.
What can I redeem my reward points for?
Points can be used to book flights and hotels, purchase gift vouchers, buy memberships, or redeem instantly at select offline and online merchants.
What is the value I get when I redeem reward points?
Each reward point holds a fixed value of Rs. 0.25. For instance, redeeming 4,000 points gives you exactly Rs. 1,000 in purchasing power.
Can I pay for my entire flight using only reward points?
No, the bank allows you to pay up to 70% of your total booking amount via reward points. The remaining balance must be paid using the credit card.
Is there a fee for redeeming my rewards?
While voucher redemptions are free on EDGE Rewards formats, a fee of Rs. 99 plus GST per transaction applies for specific partner transfers or conversions.
Is there a minimum points balance needed before I can redeem?
A minimum of 500 reward points is required to initiate redemption for gift vouchers and partner rewards.
How long does it take for redeemed vouchers to reach me?
Digital gift vouchers are delivered instantly to your registered email and mobile number upon successful redemption.
What happens to my unredeemed points if I close the card?
Unredeemed rewards are completely forfeited upon card closure. Always ensure you redeem your full points balance before initiating the cancellation process.

Gift card - Key Terms

Once you apply, we will start tracking your application
Generally takes 2-72 hrs

Once the bank confirms us of your successful card activation, we will process your rewards
Generally takes 7-75 days

You can then withdraw your rewards via Amazon Pay Balance/Flipkart gift cards
Generally takes 7-75 days
Note: If you currently hold or have ever held an IDFC Credit Card, you are not eligible for CashKaro Rewards.
Rewards Related
- If you currently hold or have ever held an IDFC Credit Card, you are not eligible for Gift Card
- A minimum transaction of Rs.100 within 30 days is mandatory to activate your card; otherwise, you wont be eligible for the Rewards
- Please use Aadhaar linked mobile number to fill the application
- If the distance between your residence and office addresses is 150 km or more, please ensure that your residence is selected as the mailing address. Applications not adhering to this will be rejected
- VKYC done over 50km from your Aadhaar/communication address will result in application rejection and loss of Rewards
Also, Remember
- Resume your application only via Great.Cards to avoid losing Rewards
- If your Rewards do not track, raise a Missing Rewards Ticket within 30 Days from the application date
- Rewards can only be redeemed as Amazon Pay Balance and Flipkart Gift Card

Bank Exclusions
You will not earn points / cashback on spends in the following categories
For Points / Cashback Earnings

Insurance premium payments
fuel spends
EMI transactions
ATM cash withdrawals
utility spends
grocery spends and IDFC FIRST FASTag recharges.
For Spends Waiver
ATM withdrawals
Insurance
EMI
Balance Transfer
Fees & Charges
Reversals/Refunds
To maximize your benefits, you must understand exactly where the IDFC FIRST Power Credit Card does not ...
Read MoreRead Less
To maximize your benefits, you must understand exactly where the IDFC FIRST Power Credit Card does not ...
To maximize your benefits, you must understand exactly where the IDFC FIRST Power Credit Card does not work. Banks place restrictions to prevent abuse of the reward system. For this card, base earning exclusions are quite broad. You will not earn any base reward points on insurance premium payments, EMI transactions, ATM cash withdrawals, balance transfers, fees, charges, or transaction reversals.
Crucially, you must understand how the categories work together. While the card offers accelerated rewards for fuel spends, utility bills, grocery spends, and IDFC FIRST FASTag recharges (up to their respective monthly caps), these categories are completely excluded from the normal base earnings. For example, if you spend Rs. 4,000 on groceries, you earn the capped 400 points. If you spend another Rs. 2,000 on groceries that same month, that extra Rs. 2,000 earns absolutely zero points because groceries do not qualify for the base 2 points per Rs. 150 rate.
View FAQ
Commonly Asked Questions
Which transactions do not earn any rewards on this card?
Transactions like insurance premium payments, EMI conversions, ATM cash withdrawals, balance transfers, and bank charges do not earn any reward points.
Are fuel transactions excluded from base rewards?
Yes, fuel spends do not earn the base 2 points per Rs. 150. They only earn points through the dedicated 3.5% HPCL category up to the 700-point limit.
Do I keep earning points if I spend Rs. 10,000 on utilities in a month?
No. Once you hit the 400-point cap on grocery and utility spends (around Rs. 4,000 spend), any further utility spending that month earns zero points.
Are insurance premium payments excluded from rewards?
Yes, paying your life or health insurance premiums with this card falls under the exclusions list and will not generate any reward points.
Does converting a purchase into an EMI affect my rewards?
Yes, the moment you convert a retail purchase into an EMI transaction, it becomes ineligible for reward points, and any points initially credited are reversed.
Do wallet top-ups earn rewards on this card?
Wallet recharges do not accrue reward points, as loading money into digital wallets falls under quasi-cash transactions and is excluded from reward earnings.
What happens if I accidentally make a payment in an excluded category?
The payment will process successfully just like any standard transaction, but your account will not accrue any reward points for that specific spend.
Are refunds counted against my reward balance?
Yes, if you buy an item, earn points, and later return it for a refund, the bank will deduct the equivalent reward points from your account balance.

Bank Fee Structure
| Structure | Details |
|---|---|
Forex Markups  3.5% forex markup is charged on transactions made in currencies other than INR. Applies to international POS payments and online purchases charged in foreign currency. | 3.50% |
APR Fees Interest rates are dynamic and range from 0.71% to 3.85% per month (8.5%–46.2% p.a.). | 3.85% |
ATM withdrawal A ₹199 fee is charged per domestic cash withdrawal, with 0% interest until the due date (up to 45 days). | ₹199 |
Reward Redemption Fees A reward redemption handling fee of ₹99 plus applicable GST is charged per redemption request. | ₹99 |
Link for all T&Cs | Click Here |
Railway Surcharge 1% fee beyond ₹25,000 Passenger Railway spends per statement cycle; platform charges extra. | 1% |
Rent Payment Fees 1% of the transaction amount is charged as a fee on rent payment transactions, subject to applicable GST and platform charges | 1% |
cheque Payment Fees No cheque payment fee is charged | N/A |
Cash Payment Fees N/A | N/A |
| Late Payment Fees | Amount Due |
|---|---|
| ₹0 - ₹100 | ₹0 |
| ₹500 | ₹100 |
| ₹5000 | ₹750 |
| ₹8000 | ₹1200 |
| ₹10,000 | ₹1300 |
| ₹10,000 & above | ₹1300 |
Understanding the exact costs associated with the IDFC FIRST Power Credit Card ensures you don't lose y...
Read MoreRead Less
Understanding the exact costs associated with the IDFC FIRST Power Credit Card ensures you don't lose y...
Understanding the exact costs associated with the IDFC FIRST Power Credit Card ensures you don't lose your reward earnings to unexpected penalties. Below is a detailed breakdown of every fee associated with this card, proving why responsible usage is key.
The Joining Fee is set at Rs. 199 plus GST. This is a one-time charge billed to your first statement to activate the card. This fee is easily offset if you spend Rs. 250 on HPCL fuel within 60 days to trigger the welcome voucher, and it is entirely reversed if you spend Rs. 50,000 in your first anniversary year.
The Annual or Renewal Fee is also Rs. 199 plus GST, applying from the second year onward. You can completely avoid this charge if your total card spends in the preceding year cross the Rs. 50,000 mark. For instance, spending an average of Rs. 4,200 per month guarantees a fee waiver.
The APR (Interest Rate) is fixed at 3% per month. This finance charge activates only if you fail to pay your total outstanding balance by the due date. For example, if you carry forward a balance of Rs. 10,000, you will be charged roughly Rs. 300 in interest for that month, which completely wipes out any rewards you earned.
Late Payment Charges apply if you fail to pay even the Minimum Amount Due. The fee scales with your outstanding balance: Rs. 0 for balances up to Rs. 500; Rs. 500 for balances between Rs. 501 and Rs. 5,000; Rs. 750 for balances between Rs. 5,001 and Rs. 10,000; and Rs. 1,200 for balances above Rs. 10,000. If your bill is Rs. 6,000 and you miss the deadline, you pay a Rs. 750 penalty plus the 3% interest.
The Forex Markup Fee is 2% on all international transactions. This applies to swiping your card abroad or buying from foreign websites in non-INR currencies. If you purchase a software subscription online for USD 100 (roughly Rs. 8,300), the bank will add a Rs. 166 forex markup fee to your bill.
The ATM Cash Withdrawal Fee is Rs. 250 per transaction. Interest at the 3% monthly rate begins accruing immediately from the moment of withdrawal. Always use digital payment methods to avoid these high costs.
A Rent Payment Convenience Fee of 1% is charged on the total transaction amount when you use the card to pay rent via third-party platforms. If your monthly rent is Rs. 20,000, the bank will charge an extra Rs. 200, plus GST, rendering rent payments highly unprofitable on this card.
For Railway Surcharges, the fee is applied as prescribed by IRCTC or Indian Railways when booking or cancelling tickets. If IRCTC mandates a 1% surcharge on a Rs. 2,000 ticket, you will pay an extra Rs. 20.
A Cash Payment Fee of Rs. 175 is applied per deposit if you choose to pay your credit card bill by physically depositing cash at a bank branch. Always pay digitally via UPI or net banking to avoid this cost.
There is No Cheque Payment Fee charged by the bank. If you prefer to drop a cheque in an ATM drop box to clear your bill, you will not face any processing charges for this method.
A Reward Redemption Fee of Rs. 99 plus GST applies per transaction for partner transfers or conversions. While voucher redemptions are free on EDGE Rewards, moving points to specific external partners will cost you Rs. 99, reducing the net value of your stash.
| Fee Type | Amount / Rate |
|---|---|
| Joining Fee | Rs. 199 + GST (Reversed on Rs. 50,000 spend) |
| Annual Fee | Rs. 199 + GST (Waived on Rs. 50,000 spend) |
| Interest Rate (APR) | 3% per month |
| Late Payment Fee | Rs. 0 to Rs. 1,200 (based on balance) |
| Forex Markup | 2% of transaction value |
| Rent Payment Fee | 1% of transaction amount |
| Cash Bill Payment | Rs. 175 per deposit |
| Cheque Bill Payment | Nil |
| Reward Redemption Fee | Rs. 99 + GST (for partner conversions) |
View FAQ
Commonly Asked Questions
What are the joining fees for this card?
The card charges a joining fee of Rs. 199 plus GST, which is billed in your first statement.
What is the annual or renewal fee?
The annual renewal fee is Rs. 199 plus GST, applicable from the second year onwards.
Is there an annual fee waiver based on spending?
Yes, the annual fee is waived if you spend Rs. 50,000 or more in a year on your card.
How can I get this card lifetime free?
The bank provides lifetime free offers for select corporate accounts and during specific festive promotions.
What is the interest rate if I don't pay my full balance?
The card charges a 3% per month interest rate on any unpaid outstanding balances.
How is the interest calculated on outstanding balances?
Finance charges of 3% per month apply on unpaid balances daily until the full amount is completely repaid. For a Rs. 5,000 balance, you pay exactly Rs. 150 a month in interest.
What are the late payment charges?
Late fees are tiered: Rs. 0 for balances up to Rs. 500; Rs. 500 for balances up to Rs. 5,000; Rs. 750 up to Rs. 10,000; and Rs. 1,200 for balances above Rs. 10,000.
What is the forex markup for international transactions?
A 2% forex markup is charged on transactions made in currencies other than INR. Spending Rs. 5,000 abroad will incur a Rs. 100 fee.
Can I withdraw cash using my credit card?
Cash withdrawals attract a flat fee of Rs. 250 per transaction plus interest at 3% per month starting from the date of withdrawal.
Are there fees for paying rent with this card?
Yes, a 1% fee is applied to the transaction amount when you use this card to pay rent. A Rs. 15,000 rent payment triggers a Rs. 150 fee.
Is there a fee for paying my bill in cash?
Yes, if you visit a branch to deposit cash to clear your credit card bill, a fee of Rs. 175 is applied per deposit.
What are the charges for cheque payment of bills?
No cheque payment fee is charged by the bank for clearing your credit card dues.
Are there charges for railway ticket bookings?
Surcharges on booking or cancelling railway tickets will be levied exactly as prescribed by IRCTC or Indian Railways.
Is there a fee to redeem my reward points?
A fee of Rs. 99 plus GST applies per transaction when converting points to external partners, though voucher redemptions are free.
What happens if my payment cheque bounces?
A cheque return fee of Rs. 500 plus GST applies to each bounced payment, along with applicable late payment charges.

Documents Required
To process your application smoothly, you must provide proof of identity, address, and income. Having these ready prevents unnecessary delays.
You need your PAN Card as the primary identity document. For address proof, an Aadhaar Card, Passport, or Voter ID is acceptable. To prove your income, salaried employees should provide their latest two months' salary slips and the last three months' bank statements showing salary credits. Self-employed applicants must submit their latest Income Tax Return (ITR) computation along with business continuation proof.
View FAQ
Commonly Asked Questions
Do I need to submit physical copies of my documents?
No, if you opt for the digital Video KYC route, you only need to show your original documents to the camera; no physical photocopies are required.
Is a PAN card mandatory to apply?
Yes, a valid PAN card is strictly mandatory for all credit card applications in India to verify your credit score and financial history.
What can I use as proof of address?
Your Aadhaar card, valid Passport, Voter ID, or a recent utility bill in your name serve as acceptable proof of address.
How many months of salary slips do I need?
Salaried applicants need to upload their most recent two months' salary slips clearly showing a minimum net income of Rs. 25,000 per month.
What documents do self-employed individuals need?
Self-employed applicants must submit their latest Income Tax Return (ITR) documents demonstrating a minimum annual income of Rs. 3 Lakhs.
Can I apply using my business address instead of my home address?
You must provide your permanent residential address for KYC, though you can request the physical card to be delivered to your verified office address.
Is Aadhaar mandatory for the application?
While Aadhaar makes e-KYC instantaneous and is highly recommended, you can use other valid government IDs for physical KYC processing.

Who Should Get This Card?
The Commuter Profile: If you drive to work every day and consistently refuel at HPCL stations, this card is a no-brainer. The 5% combined return on fuel heavily reduces your monthly transit budget.
The Household Manager: Managing a home involves steep grocery and electricity bills. Earning 2.5% back on these exact categories without paying a premium Rs. 1,000+ annual fee makes this card a highly logical addition to your wallet.
Who should skip it? If you fly frequently, dine out at luxury restaurants, or prefer IndianOil or Bharat Petroleum pumps, skip this card. The base reward rate of 0.33% is too low for a general-purpose shopper. You are better off looking at travel-focused or flat-rate cashback cards.

Credit Limit and What to Expect
Your credit limit is not a fixed number for all applicants; it is tailored directly to your financial profile. When reviewing your application, IDFC FIRST assesses your monthly salary or ITR, existing debt obligations, and your 720+ credit score. If you have an existing relationship with the bank or a robust credit history with high limits on other cards, expect a more generous limit. New credit users should expect a modest starting limit, which increases after six months of responsible usage and timely payments.
View FAQ
Commonly Asked Questions
How does the bank determine my credit limit?
Your limit is decided based on your declared income (Rs. 25,000/month or Rs. 3 Lakh/year minimum), your credit score, and any outstanding loans you currently hold.
Can I request a higher limit right after approval?
Initial limits are fixed. You need to use the card responsibly for at least 6 months before the bank considers a limit enhancement request.
Will using my full limit negatively affect my credit score?
Yes, maxing out your card increases your credit utilization ratio. Keeping your usage below 30% of your total limit is considered good practice for maintaining a 720+ score.
Does the bank offer limit increases automatically?
Yes, banks frequently review accounts. If you pay your bills on time and your income profile supports it, they may offer an automatic limit upgrade.
What happens if I accidentally spend over my credit limit?
The bank charges an over-limit fee of 2.5% of the over-limit amount, with a minimum of Rs. 500. Over-limit transactions are either declined or approved with this penalty fee attached to your next statement.
Can I set my own daily spending limits?
Yes, through the IDFC FIRST Mobile App, you can easily set and modify transaction limits for online, offline, and contactless payments for security.

How to Apply?
Getting your hands on this card is a fully digital process. You can apply directly via the IDFC FIRST Bank official website or through verified financial partner platforms. Once you fill in your basic personal and professional details, the system will run a soft check to confirm your eligibility. If approved in principle, you will be directed to complete a Video KYC call. Ensure you have your original PAN card handy, sit in a well-lit room, and maintain a stable internet connection. Completing Video KYC eliminates the need for any physical document pickup.
View FAQ
Commonly Asked Questions
Where can I apply for this credit card?
You can apply online through the official IDFC FIRST Bank website, partner platforms, or by visiting a local bank branch.
What is Video KYC and is it mandatory?
Video KYC is a secure digital verification call with a bank agent. It is mandatory as it allows you to complete your application instantly without physical paperwork.
What do I need for a successful Video KYC call?
Keep your original PAN card ready, ensure you are within 50km of your registered address, and use a stable internet connection in a quiet, well-lit room.
How can I track my application status?
Use the Application ID provided via SMS after submission to track your exact status on the bank's online tracking portal.
How long does the approval process take?
If your Video KYC is successful and documents match, final approval takes 3 to 5 working days, after which the physical card is dispatched.
Do I need to visit a branch to complete the application?
No, if you successfully complete the Video KYC process online, there is no need to visit a physical bank branch.
What happens if my Video KYC fails?
If Video KYC fails due to connectivity or location issues, the bank will arrange for a physical executive to visit your address to collect KYC documents.

That’s the full story of this credit card
Like this card? Your apply button’s just there.
Top Benefits


Apply and get ₹750 Rewards
Top Benefits
Get Fuel Welcome Cashback on the first HPCL fuel
transaction of ₹250 or more within 30 days of card setup as ₹250 cashback
5% Cashback on First EMI Conversion
get 5% cashback up to ₹1,000 on converting the first transaction to EMI

The smartest way to find your great credit card


We value your time and privacy. Your details stay secure and are used only to help you.
Company
We value your time and privacy. Your details stay secure and are used only to help you.