
SBM Bank
SBM Kredit.Pe Credit Card
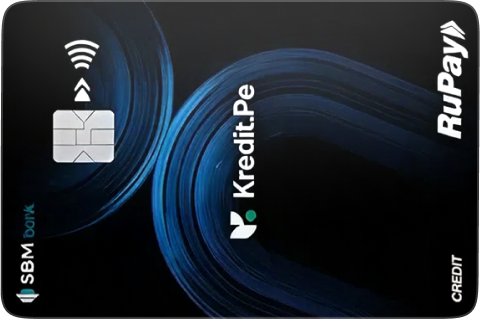
 This is an invite only card
Top Benefits

Get 3% Cashback
on every ₹100 spent on online merchant card payments on ecommerce transactions
Redeem Your Cashback for 5%, 10% or 15% Extra Discount
on popular brand vouchers like Amazon Pay, Flipkart, Myntra and more

Best For
Shopping
Online Food Ordering
UPI

The SBM Kredit.Pe Credit Card is a unique financial tool designed to merge the security of a fixed depo...
Read More Read Less

The SBM Kredit.Pe Credit Card is a unique financial tool designed to merge the security of a fixed depo...
The SBM Kredit.Pe Credit Card is a unique financial tool designed to merge the security of a fixed deposit with the everyday convenience of RuPay UPI payments. If you want a straightforward way to build your credit score while earning solid cashback on your daily UPI scans, this card delivers a clear value proposition. Because it is an FD-backed credit card, you do not need to provide income proofs or salary slips, making it highly accessible to students, freelancers, and self-employed professionals.
What sets this card apart from traditional credit cards is its strong focus on UPI rewards. Instead of juggling a debit card and a separate credit card for store purchases, you can link the SBM Kredit.Pe card directly to your favorite UPI app. You earn up to 3% cashback on these daily transactions. Furthermore, the barrier to entry is extremely low. By simply opening a fixed deposit of Rs. 5,000 or more, you automatically waive the Rs. 199 annual fee, making the card virtually cost-free to hold while your deposit continues to earn interest.
View FAQ
Commonly Asked Questions
Is the SBM Kredit.Pe Credit Card lifetime free?


The card has a zero joining fee. The annual fee is Rs. 199 plus GST, but this is completely waived if you link a fixed deposit of Rs. 5,000 or more. If you maintain that FD, the card effectively acts as a lifetime free option.
Who should apply for this card?
This card is perfect for students, homemakers, and self-employed individuals who do not have standard income proofs. Because it is backed by a fixed deposit, approval is smooth, making it an excellent choice for building or repairing your credit history.
Is this a good first card for building credit?
Yes, it is an outstanding first card. Since it is secured by your fixed deposit, you get assured approval. Regular use and timely bill payments will report positively to credit bureaus, helping you establish a strong credit score from scratch.
Can I use this card for UPI payments?
Absolutely. Since it is issued on the RuPay network, you can link this credit card to UPI applications. This allows you to scan merchant QR codes and pay directly using your credit limit while earning cashback.

Expert Review
As a credit card expert, I view the SBM Kredit.Pe Credit Card as a highly tactical tool for a very specific demographic. Its strongest asset is the integration of RuPay UPI with a 3% cashback rate. The fact that anyone with Rs. 5,000 can get guaranteed approval and enjoy a waived annual fee makes it a fantastic starter card for students and self-employed people looking to build a CIBIL score.
However, it is not without flaws. My biggest criticism is the Rs. 99 reward redemption fee. If the card caps your accelerated cashback at Rs. 500 a month, paying Rs. 99 (nearly 20% of your maximum monthly earnings) just to redeem it is a tough pill to swallow. You must hoard your cashback for months before redeeming to make the fee mathematically acceptable.
Ultimately, if you want a no-nonsense entry into the credit world and use UPI for almost every daily purchase, this card is excellent. Just be smart about when you choose to cash out your rewards.

Joining / Annual Fee
Joining Fees
₹0 ( ₹0 + GST )

Annual Fees
₹235 ( ₹199 + GST )
Understanding the cost of holding a credit card is vital for long-term savings. The SBM Kredit.Pe Credi...
Read MoreRead Less
Understanding the cost of holding a credit card is vital for long-term savings. The SBM Kredit.Pe Credi...
Understanding the cost of holding a credit card is vital for long-term savings. The SBM Kredit.Pe Credit Card stands out because it charges absolutely zero joining fees. You do not pay anything upfront to get the physical plastic card issued to you.
Starting from the second year, an annual fee of Rs. 199 plus GST applies. However, avoiding this fee is incredibly simple. The annual fee is entirely waived if the fixed deposit linked to your card is Rs. 5,000 or more. Since Rs. 5,000 is a highly accessible threshold for an FD, practically every user can hold this card for free. For example, if you place Rs. 10,000 in an FD to get a decent credit limit, your annual fee becomes Rs. 0 automatically. If, for some reason, your FD drops below Rs. 5,000, you will be billed the Rs. 199 fee. This transparent structure ensures you are never caught off guard by hidden renewal charges.
View FAQ
Commonly Asked Questions
What are the joining fees for this card?
The joining fee is Rs. 0. You do not have to pay any issuance fee when you apply for the card.
Is there a welcome bonus to offset the joining fee?
Even though the joining fee is zero, you still get a Rs. 200 cashback welcome bonus upon card activation, putting you in immediate profit.
What is the annual or renewal fee?
The standard annual fee is Rs. 199 plus GST, charged from the second year onwards.
Is there an annual fee waiver option?
Yes, the annual fee is automatically waived if your linked fixed deposit is Rs. 5,000 or higher.
What happens if my FD is only Rs. 2,000?
If your linked FD is below the Rs. 5,000 threshold, you will be charged the Rs. 199 plus GST annual fee on your renewal date.
Do I have to spend a certain amount to waive the annual fee?
No, the fee waiver is not based on your yearly card spends. It is based entirely on maintaining an FD of Rs. 5,000 or more.
From when is the annual fee charged?
If applicable, the annual fee is charged at the end of your first 12 months of card membership.
How can I get this card lifetime free?
Simply open and maintain a fixed deposit of Rs. 5,000 or more with the bank. As long as the FD remains active at that amount, your card functions as a lifetime free product.
Is GST charged on the annual fee?
Yes, if you do not meet the waiver criteria, an 18% GST will be applied on top of the Rs. 199 annual fee, making the total charge roughly Rs. 234.

Eligibility
Age
Criteria*
18-60 years
Salary
Criteria*
0LPA
Credit
Rating*
720+
New to credit
allowed
Yes
Existing Bank
Customer Allowed
No
Securing an SBM Kredit.Pe Credit Card is a smooth, stress-free process primarily because it functions a...
Read MoreRead Less
Securing an SBM Kredit.Pe Credit Card is a smooth, stress-free process primarily because it functions a...
Securing an SBM Kredit.Pe Credit Card is a smooth, stress-free process primarily because it functions as an FD-backed card. The bank requires the primary applicant to be at least 18 years old, making it ideal for college students or young adults taking their first steps in personal finance. The maximum age limit to apply is 60 years.
One of the biggest hurdles in getting a credit card is providing salary slips or Income Tax Returns. This card removes that barrier entirely. There is a zero minimum monthly income requirement for salaried applicants, and a zero minimum annual income requirement for self-employed individuals. This means you could be a freelancer earning varied amounts monthly or a homemaker with no formal income, and you are still eligible. The bank looks favorably on a minimum CRIF credit score of 720. However, since your credit limit is secured against your fixed deposit, the strictness around credit scores is greatly reduced compared to unsecured cards.
Here is a quick breakdown of the requirements:
- Minimum Age: 18 years
- Maximum Age: 60 years
- Income Requirement (Salaried): Rs. 0 (No income proof required)
- Income Requirement (Self-Employed): Rs. 0 (No income proof required)
- Preferred Credit Score: 720 CRIF score
- Security Requirement: Must open a linked Fixed Deposit
View FAQ
Commonly Asked Questions
What is the minimum age to apply for this card?
You must be at least 18 years old to apply, making it an excellent option for young adults and college students.
What is the maximum age limit for the primary cardholder?
The maximum age limit at the time of application is 60 years.
What is the minimum salary required for salaried applicants?
There is zero salary requirement. Because this is an FD-backed card, you do not need to provide any monthly income proof.
What is the minimum annual income for self-employed applicants?
Self-employed professionals face a zero income requirement as well. You do not need to submit ITR documents to get approved.
Do I need a high credit score to get approved?
While the bank prefers a CRIF score of 720, the FD-backed nature of the card means approval is practically assured even if you are new to credit or have a lower score.
Can college students apply for this card?
Yes, as long as the student is 18 years old and can open the required fixed deposit, they are fully eligible to apply.
Will my application be rejected if I have no credit history?
No, having zero credit history is fine. This card is specifically designed to help people build their credit scores from scratch.
Do I need to be an Indian citizen to apply?
Yes, standard eligibility requires you to be a resident Indian. Currently, the card is available exclusively to resident Indians; NRI applications are not processed at this stage.
What happens if my CRIF score is exactly 720?
A score of 720 meets the preferred criteria perfectly, ensuring an even smoother onboarding and approval process.

All Card Benefits
- Earn 3% cashback on all offline (PoS) and online (Ecom) card payments
- Earn 3% cashback on UPI payments via Kredit.Pe app
- Earn 5% cashback on Kredit.Pe UPI spends above ₹10,000 per month; capped at ₹500 per month
- Redeem cashback for 5% discount on digital gold; or 5%, 10% or 15% discount on popular vouchers (AmazonPay, Swiggy, Zomato, Flipkart, Zepto & more) via Kredit.Pe app
- FD of ₹10,000 or above unlocks extra 20% discounts on vouchers & digital gold
Welcome Benefits
Getting started with the SBM Kredit.Pe Credit Card gives you an immediate financial...
Read MoreRead Less
Welcome Benefits Getting started with the SBM Kredit.Pe Credit Card gives you an immediate financial...
Welcome Benefits
Getting started with the SBM Kredit.Pe Credit Card gives you an immediate financial boost. Upon successfully activating your card, you receive a flat Rs. 200 cashback joining bonus. Since the card carries zero joining fees, this bonus is pure profit in your pocket. For example, if you make your first transaction of Rs. 500 to buy groceries, the Rs. 200 cashback effectively reduces your cost for that trip to just Rs. 300. It is a simple, hassle-free way to begin your reward journey.
Cashback and Reward Points Structure
The core strength of the SBM Kredit.Pe card lies in its generous cashback rates, specifically tailored for the modern Indian consumer who relies heavily on UPI and online shopping. You earn an impressive 3% cashback on plastic card transactions at physical stores and online portals. Furthermore, if you spend over Rs. 10,000 in a month via Kredit.Pe UPI, you earn 3% cashback on those transactions as well. If you make bank account UPI transactions via Kredit.Pe, you get a solid 2% cashback.
To understand the math, let us look at a practical scenario. Suppose you spend Rs. 15,000 using Kredit.Pe UPI at local merchants and Rs. 5,000 online using the physical card details. You earn 3% on the Rs. 15,000 UPI spends (Rs. 450) and 3% on the online card spends (Rs. 150). However, keep in mind that the card has a maximum cashback capping of Rs. 500 per month. Even with this cap, maximizing it every month nets you Rs. 6,000 in a year. When you use this cashback, you can stretch its value further by securing a 5% discount on digital gold purchases or up to 7% off on gold, effectively making your 1 Rupee cashback worth even more.
Dining and Shopping Voucher Benefits
While this card does not offer direct dining cashback, it provides exceptional value through the Kredit.Pe rewards catalogue. You can get up to 70% off on shopping and food delivery vouchers for massive brands like Amazon, Flipkart, Swiggy, Zomato, and Zepto. For example, if you want a Rs. 1,000 Zomato voucher and there is a 50% discount offer running on the platform, you only spend Rs. 500 worth of your balances to buy a full-value dining code. This dramatically increases your purchasing power for daily necessities and weekend food deliveries.
Fuel Surcharge Waiver Benefits
Driving a car or riding a bike involves constant fuel expenses. The SBM Kredit.Pe Credit Card helps soften this blow by offering a standard 1% fuel surcharge waiver on your petrol or diesel purchases across India. When you swipe a credit card at a pump, banks usually apply a 1% surcharge. With this card, that fee is waived. If you spend Rs. 3,000 on fuel in a month, you save Rs. 30 in unnecessary extra charges. Over a year, that is Rs. 360 saved just by using the right payment method.
View FAQ
Commonly Asked Questions
How do I qualify for the welcome bonus?
You qualify for the Rs. 200 welcome bonus simply by completing your card activation. Complete your first transaction within 30 days of activation to ensure the bonus is triggered.
Is there a joining fee to get this welcome benefit?
No, the card has a joining fee of Rs. 0. This means you do not pay any upfront cost to access the Rs. 200 welcome cashback.
How is the welcome bonus credited?
The Rs. 200 is credited as cashback. This can be used to offset your statement balance or redeemed against available options like digital gold on the Kredit.Pe platform.
When will I receive the welcome benefit after card activation?
The cashback is processed and reflects in your account within 7 to 10 working days after successful activation.
Can I get this bonus every year?
No, the Rs. 200 cashback is a one-time joining bonus provided only when you activate your new credit card for the first time.
What is the standard reward rate on this card?
You earn up to 3% cashback on Kredit.Pe UPI (for monthly spends over Rs. 10,000) and 3% on plastic card spends online and offline. Bank account UPI transactions via Kredit.Pe earn 2% cashback.
What is the value of 1 cashback point in rupees?
The conversion rate is straightforward: 1 Cashback rupee equals exactly Rs. 1. You do not have to deal with confusing fractional point values.
Is there a limit to how much cashback I can earn?
Yes, there is a maximum cashback cap of Rs. 500 per month across the accelerated categories. Once you hit this limit, standard earning rules apply.
Do I earn cashback on utility bill payments?
No, utility bill payments are part of the excluded categories and will not earn any cashback on this card.
Do I earn cashback on rent payments?
No, rent payments are explicitly excluded from earning any cashback, and they also attract a 1% processing fee.
Are education expenses eligible for rewards?
No, education spends do not accumulate any cashback on the SBM Kredit.Pe Credit Card.
What happens if I spend less than Rs. 10,000 on UPI in a month?
The 3% cashback on Kredit.Pe UPI requires a minimum spend of Rs. 10,000 per month. Spends below this threshold earn a base reward rate of 0.5% cashback.
How do I maximize my Rs. 500 monthly limit?
To hit the Rs. 500 cap at a 3% reward rate, you need to spend approximately Rs. 16,666 across eligible retail and online categories in a month.
Can I use my cashback to buy gold?
Yes, one of the unique features is using your earned cashback to get a 5% discount on digital gold purchases, or up to 7% off on gold via the app.
Do my earned cashback rupees expire?
Your accumulated cashback balance remains valid for 24 months from the date of accrual, giving you ample time to redeem your rewards.
Which transactions do not earn any cashback?
You will not earn cashback on rent, ATM withdrawals, wallet loads, education, agriculture, utility bills, transportation, and government-related transactions.
Can I transfer my cashback to another bank account?
Cashback is meant for platform redemption like vouchers and digital gold. Direct bank transfers are not permitted as per current platform rules.
Do I get direct discounts at restaurants?
No, the card does not offer direct restaurant billing discounts. Instead, you get up to 70% off when purchasing Zomato and Swiggy vouchers through their platform.
Which shopping vouchers are available?
You can access discounted vouchers for popular platforms including Amazon Pay, Flipkart, and Zepto for your daily grocery and shopping needs.
How much can I save on a Swiggy voucher?
Discounts vary by current promotions, but you can get up to 70% off. For a Rs. 500 Swiggy voucher, you might pay as little as Rs. 150 depending on the active offer.
Are these vouchers available instantly?
Yes, digital vouchers purchased through the Kredit.Pe catalogue are delivered to your registered email or phone instantly.
Can I buy groceries with these benefits?
Absolutely. You can purchase discounted vouchers for Amazon Pay or Zepto, which can then be used to order everyday groceries, saving you significant money over time.
Does this card give free petrol?
No, it provides a 1% surcharge waiver, which removes the extra processing fee normally charged when using a credit card at fuel stations.
Is there a minimum transaction amount to get the waiver?
The 1% fuel surcharge waiver is applicable on transactions ranging from Rs. 400 to Rs. 4,000 across all fuel stations.
Is there a monthly cap on fuel surcharge savings?
The maximum fuel surcharge waiver is capped at Rs. 200 per statement cycle, allowing you to save significantly on monthly fuel bills.
Do I earn 3% cashback on fuel purchases?
No, fuel purchases receive the 1% surcharge waiver and do not count toward your regular 3% cashback earning categories.
Can I get the waiver at any petrol pump?
Yes, the 1% fuel surcharge waiver is valid across all authorized petrol pumps in India, regardless of the brand.

How to Redeem Rewards & Cashback?
Rewards Conversion Rate
N/A

Redemption Options
This is a cashback card, and the earned cashback is adjusted directly in your monthly statement.
To check redemption catalogue
N/A
Earning cashback is only half the journey; redeeming it easily is what makes a credit card truly valuab...
Read MoreRead Less
Earning cashback is only half the journey; redeeming it easily is what makes a credit card truly valuab...
Earning cashback is only half the journey; redeeming it easily is what makes a credit card truly valuable. The SBM Kredit.Pe Credit Card keeps things crystal clear: 1 Cashback Rupee is worth exactly Rs. 1. You do not have to divide your points by 4 or 10 to figure out their real-world value.
To redeem, you log into the Kredit.Pe platform (https://www.kredit.pe/). Here, you have two primary ways to use your earnings. First, you can use your cashback to buy digital gold, enjoying a special 5% discount on the purchase, or even get up to 7% off on gold using cashback. Second, you can browse a catalogue of top-tier shopping and dining vouchers including Amazon Pay, Swiggy, Zomato, Flipkart, and Zepto. Note that the bank charges a reward redemption fee of Rs. 99 plus GST every time you make a redemption request. For example, if you have accumulated Rs. 1,000 in cashback and you redeem it for a Flipkart voucher, you will be billed Rs. 99 plus GST on your next statement for processing the reward.
View FAQ
Commonly Asked Questions
How do I redeem the cashback I have earned?
You must log into the Kredit.Pe portal or app. From there, you can choose to redeem your cashback rupees for vouchers or digital gold.
What is the value I get when I redeem my cashback?
The value is perfectly transparent. 1 Cashback rupee equals Rs. 1. So, 500 cashback points will buy you exactly Rs. 500 worth of value.
What can I redeem my rewards for?
You can redeem them for digital gold at a discount, or for popular vouchers like Amazon Pay, Flipkart, Swiggy, Zomato, and Zepto.
Is there a fee for redeeming my rewards or cashback?
Yes, a reward redemption handling fee of Rs. 99 plus applicable GST is charged per redemption request. It is best to redeem larger amounts at once to minimize the impact of this fee.
Can I adjust the cashback against my monthly bill?
Direct statement credit adjustments are not available; rewards are exclusively redeemable for brand vouchers and digital gold on the platform.
Do I get extra benefits when buying gold with cashback?
Yes, using your cashback to buy digital gold gives you a 5% discount, and you can get up to 7% off on gold through specific platform offers.
Is there a minimum cashback balance needed before I can redeem?
You can initiate redemption once your balance reaches a minimum of 100 cashback rupees. However, waiting for a higher balance is recommended due to the redemption fee.
What happens to my unredeemed cashback if I close the card?
Unredeemed cashback is forfeited when a card is closed. You should redeem all your earnings before initiating a cancellation request.

Bank Exclusions
You will not earn points / cashback on spends in the following categories
For Points / Cashback Earnings

Rent Payment
ATM Cash Withdrawals
Financial Charges
Wallet Loads
Education Spends
Agriculture
Contracted Services
Transportation
Utility Bill Payments
Government-related Transactions
For Spends Waiver
Rent Payment
ATM Cash Withdrawals
Financial Charges
Wallet Loads
Education Spends
Agriculture
Contracted Services
Transportation
Utility Bill Payments
Government-related Transactions
Credit cards do not reward every single type of transaction, and the SBM Kredit.Pe card has a clearly d...
Read MoreRead Less
Credit cards do not reward every single type of transaction, and the SBM Kredit.Pe card has a clearly d...
Credit cards do not reward every single type of transaction, and the SBM Kredit.Pe card has a clearly defined list of categories that are excluded from earning cashback. It is crucial to know these so you do not spend heavily expecting a 3% return, only to get zero.
Transactions such as rent payments, ATM cash withdrawals, and wallet loads do not earn any rewards. This means if you load Rs. 5,000 into a digital wallet, you earn Rs. 0 in cashback. Similarly, utility bill payments like your electricity or water bills, education spends (school and college fees), agriculture, contracted services, transportation, and government-related transactions are fully excluded. Furthermore, financial charges like late fees or interest applied by the bank itself will not generate cashback. Always check your spend category to ensure you are swiping for maximum benefits.
View FAQ
Commonly Asked Questions
Which transactions do not earn cashback on this card?
You will not earn cashback on rent, ATM withdrawals, wallet loads, education spends, agriculture, contracted services, transportation, utility bills, financial charges, and government transactions.
Does paying rent with this card earn reward points?
No, rent payments are strictly excluded from earning cashback. In addition, rent transactions attract a 1% processing fee.
Are utility bill payments such as electricity excluded from rewards?
Yes, utility bill payments are part of the exclusion list and will not earn the 3% or 2% cashback rates.
Do wallet top-ups earn rewards on this card?
No, transferring money to mobile wallets is treated as a quasi-cash transaction and does not earn any cashback.
Are school or college fee payments excluded from earning rewards?
Yes, education spends are completely excluded from the reward program on this card.
Will I earn cashback if I use the card to pay taxes?
No, tax payments fall under government-related transactions, which are excluded from earning any cashback.
What happens if I accidentally make a payment in an excluded category?
The transaction will process normally and be added to your monthly bill, but you simply will not earn any cashback for that specific amount.
Does withdrawing cash from an ATM give me cashback?
No, ATM cash withdrawals never earn rewards and actually cost you a flat Rs. 199 withdrawal fee.

Bank Fee Structure
| Structure | Details |
|---|---|
Forex Markups  3.5% forex markup is charged on transactions made in currencies other than INR. Applies to international POS payments and online purchases charged in foreign currency. | 3.50% |
APR Fees Finance charges of 3.75% per month (45% per annum) apply on unpaid outstanding balances until the amount is fully repaid | 3.75% |
ATM withdrawal 2.5% of the withdrawn amount is charged on cash advances using the credit card (minimum ₹500, if applicable). | 2.50% |
Reward Redemption Fees No fee is charged when redeeming reward points on this card. | Not Applicable |
Link for all T&Cs | Click Here |
Railway Surcharge Surcharge on booking or cancelling railway tickets will be levied as prescribed by IRCTC or Indian Railways and may vary based on their applicable charges. | As prescribed by IRCTC / Indian Railways |
Rent Payment Fees 1% of the transaction amount is charged as a fee on rent payment transactions, subject to applicable GST and platform charges | 1% |
cheque Payment Fees A fee of ₹100 is charged for payments made through cheque | ₹100 |
Cash Payment Fees A fee of ₹100 is charged for payments made through cash | ₹100 |
| Late Payment Fees | Amount Due |
|---|---|
| ₹0 - ₹500 | ₹50 |
| ₹501 - ₹5000 | 5% |
| ₹5001 - ₹10000 | 5% |
| ₹10001 and above | ₹ 1000 |
Understanding every fee attached to your credit card protects you from billing surprises. While the S...
Read MoreRead Less
Understanding every fee attached to your credit card protects you from billing surprises. While the S...
Understanding every fee attached to your credit card protects you from billing surprises. While the SBM Kredit.Pe Credit Card is highly affordable due to its low entry barrier, there are still specific charges applied for late payments, international usage, and special transaction types. Below is a detailed breakdown of every cost.
The joining fee for this card is Rs. 0. You can get the card issued without paying any upfront cost, and you even receive a Rs. 200 welcome cashback.
The annual or renewal fee is Rs. 199 plus GST. However, this fee is entirely waived as long as you maintain a linked Fixed Deposit of Rs. 5,000 or more. For example, if you keep a Rs. 5,000 FD running, your monthly fee cost is zero.
The APR or interest rate ranges from 0.71% to 3.85% per month (8.5% to 46.2% annually). If you have a bill of Rs. 10,000 and you only pay the minimum amount, the remaining balance will accrue interest at up to 3.85% per month, adding roughly Rs. 385 to your next bill just in interest.
Late payment charges apply if you miss your due date. The penalty is Rs. 0 for balances up to Rs. 100; Rs. 100 for balances up to Rs. 500; Rs. 750 for balances up to Rs. 5,000; Rs. 1,200 for balances up to Rs. 8,000; and Rs. 1,300 for balances above Rs. 8,000. If your outstanding balance is Rs. 3,000 and you miss the payment, you will face a Rs. 750 penalty on your next statement.
A forex markup fee of 3.5% applies to any international transactions or foreign currency online purchases. If you travel abroad and swipe your card for a hotel room costing equivalent to Rs. 10,000, the bank will charge an extra Rs. 350 just for processing the foreign currency.
The ATM cash withdrawal fee is a flat Rs. 199 per domestic withdrawal. While you get up to 45 days of 0% interest on the withdrawn amount, pulling Rs. 2,000 out of an ATM will instantly cost you Rs. 199, making it a very expensive way to access cash.
A rent payment convenience fee of 1% is charged on the transaction amount. If you use your credit card to pay a landlord Rs. 15,000 via a rental platform, the bank will levy a fee of Rs. 150 plus applicable GST on your statement.
A passenger railway surcharge of 1% applies to railway spends exceeding Rs. 25,000 per statement cycle. If you book train tickets worth Rs. 30,000 in a month, the Rs. 5,000 over the limit will attract a Rs. 50 fee. (Platform charges apply extra).
Cash payments at bank branches are not supported; all card bill payments must be made via digital channels to ensure successful clearing and zero handling fees.
The bank does not levy any additional processing fees for cheque payments. Paying your credit card bill via a dropped cheque will not attract extra processing charges.
A reward redemption fee of Rs. 99 plus GST is charged every time you submit a redemption request. If you redeem Rs. 200 worth of cashback, losing Rs. 99 to a fee destroys half your value. It is critical to accumulate a large amount before redeeming.
| Fee Type | Amount / Rate |
|---|---|
| Joining Fee | Rs. 0 |
| Annual Fee | Rs. 199 (Waived if FD > Rs. 5,000) |
| Interest Rate (APR) | 0.71% - 3.85% per month |
| Late Payment Charges | Up to Rs. 1,300 based on balance slab |
| Forex Markup Fee | 3.5% |
| ATM Withdrawal Fee | Rs. 199 per transaction |
| Rent Payment Fee | 1% of transaction amount |
| Railway Surcharge | 1% on spends beyond Rs. 25,000 |
| Reward Redemption Fee | Rs. 99 + GST |
View FAQ
Commonly Asked Questions
What are the joining fees for this card?
The one-time joining fee is Rs. 0, meaning you pay nothing to acquire the card.
What is the annual or renewal fee?
The annual fee is Rs. 199 plus GST, charged from the second year.
Is there an annual fee waiver based on spending?
No, the waiver is not based on your retail spends. It is exclusively waived if your linked fixed deposit is Rs. 5,000 or greater.
How can I get this card lifetime free?
Ensure your linked fixed deposit never drops below Rs. 5,000. As long as you maintain that minimum FD, the card acts as lifetime free.
What is the interest rate (APR) if I don't pay my full balance?
The interest rate follows a tiered structure ranging from 0.71% to 3.85% per month based on your profile and spending patterns.
How is the interest calculated on outstanding balances?
Interest is calculated daily on the unpaid balance. If you leave Rs. 10,000 unpaid at a 3.85% monthly rate, expect Rs. 385 in interest charges on your next cycle.
What are the late payment charges?
Late fees are structured in slabs ranging from Rs. 0 to a maximum of Rs. 1,300, depending on the size of your outstanding statement balance.
Is the late payment fee different based on outstanding amount?
Yes. A balance of Rs. 400 attracts a Rs. 100 fee, while a balance of Rs. 15,000 will attract the highest slab penalty of Rs. 1,300.
What is the forex markup for international transactions?
The bank charges a 3.5% markup fee. Spending Rs. 5,000 on a foreign website will result in a Rs. 175 markup charge.
Can I withdraw cash using my credit card?
Yes, but a domestic withdrawal fee of Rs. 199 per transaction applies immediately.
What are the cash withdrawal charges and limits?
You pay Rs. 199 per withdrawal. The card offers 0% interest on that withdrawn cash until the due date, providing up to 45 days of interest-free liquidity.
Are there fees for paying rent with this card?
Yes, a 1% fee is charged on the transaction amount when you use the card to pay rent via third-party platforms.
What are the charges for cheque payment of bills?
There is no cheque payment fee charged by the bank if you use this method to clear your dues.
Are there charges for railway ticket bookings?
Yes, a 1% fee applies if your passenger railway spends cross Rs. 25,000 in a single statement cycle.
Is there a fee to redeem my reward points?
Yes, every time you redeem cashback, the bank deducts a Rs. 99 plus GST handling fee from your account.

Documents Required
To process your application smoothly, you must provide proof of identity, address, and income. Having these ready prevents unnecessary delays.
You need your PAN Card as the primary identity document. For address proof, an Aadhaar Card, Passport, or Voter ID is acceptable. To prove your income, salaried employees should provide their latest two months' salary slips and the last three months' bank statements showing salary credits. Self-employed applicants must submit their latest Income Tax Return (ITR) computation along with business continuation proof.
View FAQ
Commonly Asked Questions
What identity proof do I need?
You need an original, physical PAN card for the Video KYC process.
What address proof is required?
Your Aadhaar card is used digitally to verify your address and identity during the application.
Do I need to submit a salary slip?
No. Because your credit limit is backed by a fixed deposit, no salary slips or income proofs are required.
Do I need to submit my Income Tax Returns (ITR)?
No, self-employed individuals do not need to provide any ITR documentation.
Do I need passport-size photographs?
No, your photograph will be captured digitally via your smartphone camera during the Video KYC call.
Can I use a digital copy of my PAN card for Video KYC?
No, banking regulations require you to show your original physical PAN card to the agent on the video call.
What if my current address is different from my Aadhaar address?
Provide a secondary address proof such as a recent utility bill or rental agreement to the bank for VKYC verification if your current residence differs from your Aadhaar.

Who Should Get This Card?
The College Student: If you are 18, receiving monthly pocket money, and want to start building a credit score early, putting Rs. 5,000 into an FD to get this card is a genius move. It waives the fee, and you get 3% back on your canteen UPI scans.
The Freelancer / Self-Employed: If you struggle to get unsecured cards because banks reject your lack of standard salary slips, this card bypasses that headache entirely. You get the benefits of a premium RuPay card with guaranteed approval.
Who Should NOT Get This Card? If you are a high-income earner spending Rs. 50,000+ a month on luxury travel and dining, the Rs. 500 monthly cashback cap and the lack of lounge access make this card unsuitable for your lifestyle. You should look at premium unsecured travel cards instead.

Credit Limit and What to Expect
With an FD-backed credit card, your credit limit is directly tied to the amount of money you deposit. This gives you complete control over your purchasing power. If you want a higher credit limit to buy a new smartphone, you simply open a larger fixed deposit. The bank grants a credit limit that is 90% of your total deposit amount, allowing you to spend freely while your deposit earns regular bank interest in the background.
View FAQ
Commonly Asked Questions
How is my credit limit determined?
Your credit limit is based directly on the amount of your fixed deposit. You receive a credit limit equal to 90% of the total FD amount created.
Can I increase my credit limit later?
Yes, you can increase your credit limit by adding more funds to your linked fixed deposit account through the Kredit.Pe app.
Does spending my entire limit affect my credit score?
Using 100% of your limit results in high credit utilization, which can temporarily lower your credit score. It is advisable to keep utilization below 30%.
What happens if I cross my assigned credit limit?
Transactions exceeding your limit will be declined or attract an over-limit fee of 2.5% of the over-limit amount, subject to a minimum of Rs. 500.
Is my fixed deposit safe?
Yes, your FD is held securely with SBM Bank and earns interest just like a regular fixed deposit while serving as collateral for your card.
When can I withdraw my fixed deposit?
Your FD remains locked as long as the credit card is active. To withdraw the FD, you must clear all outstanding card dues and close the credit card account.
Does the bank check my CIBIL score before giving me a limit?
While a CRIF score of 720 is preferred, the limit is guaranteed by your FD, meaning extensive credit checks are minimized.

How to Apply?
Applying for the SBM Kredit.Pe Credit Card is a fully digital, straightforward process designed to save you time. You do not need to visit a physical bank branch or hand over thick stacks of photocopied documents. You can initiate the application through the official platform by providing your basic details. Once your profile is created, you select the amount you wish to place in your fixed deposit, which will determine your credit limit. Following the FD creation, you complete a quick Video KYC process from your smartphone to verify your identity.
View FAQ
Commonly Asked Questions
Where can I apply for this credit card?
You can apply directly through the official Kredit.Pe website or application portal to start your digital journey.
What is Video KYC and is it mandatory?
Video KYC is a mandatory digital verification step where a bank representative verifies your original PAN card and identity over a quick video call.
What do I need for a successful Video KYC call?
Keep your original physical PAN card and Aadhaar handy. Ensure you are in a well-lit room with a stable internet connection to avoid call drops.
Do I need to visit a branch to complete the application?
No, the entire process, including fixed deposit creation and KYC verification, is completely online and paperless.
How long does the approval process take?
Because it is an FD-backed card, approval is processed instantly. You will receive your physical card at your registered address within 7 to 10 business days after successful VKYC.
What happens if my Video KYC fails?
If your video connection drops or fails, you will receive a new link to try again or you can contact customer support for alternative verification methods.
Do I need to upload income documents during the application?
No, since the card is secured by your fixed deposit, you will not be asked to upload salary slips or ITRs.

That’s the full story of this credit card
Like this card? Your apply button’s just there.
Top Benefits
Top Benefits
Get 3% Cashback
on every ₹100 spent on online merchant card payments on ecommerce transactions
Redeem Your Cashback for 5%, 10% or 15% Extra Discount
on popular brand vouchers like Amazon Pay, Flipkart, Myntra and more

The smartest way to find your great credit card


We value your time and privacy. Your details stay secure and are used only to help you.
Company
We value your time and privacy. Your details stay secure and are used only to help you.